Connect with us

Business

Bank of England cuts rate amid tariff concerns

Published

on

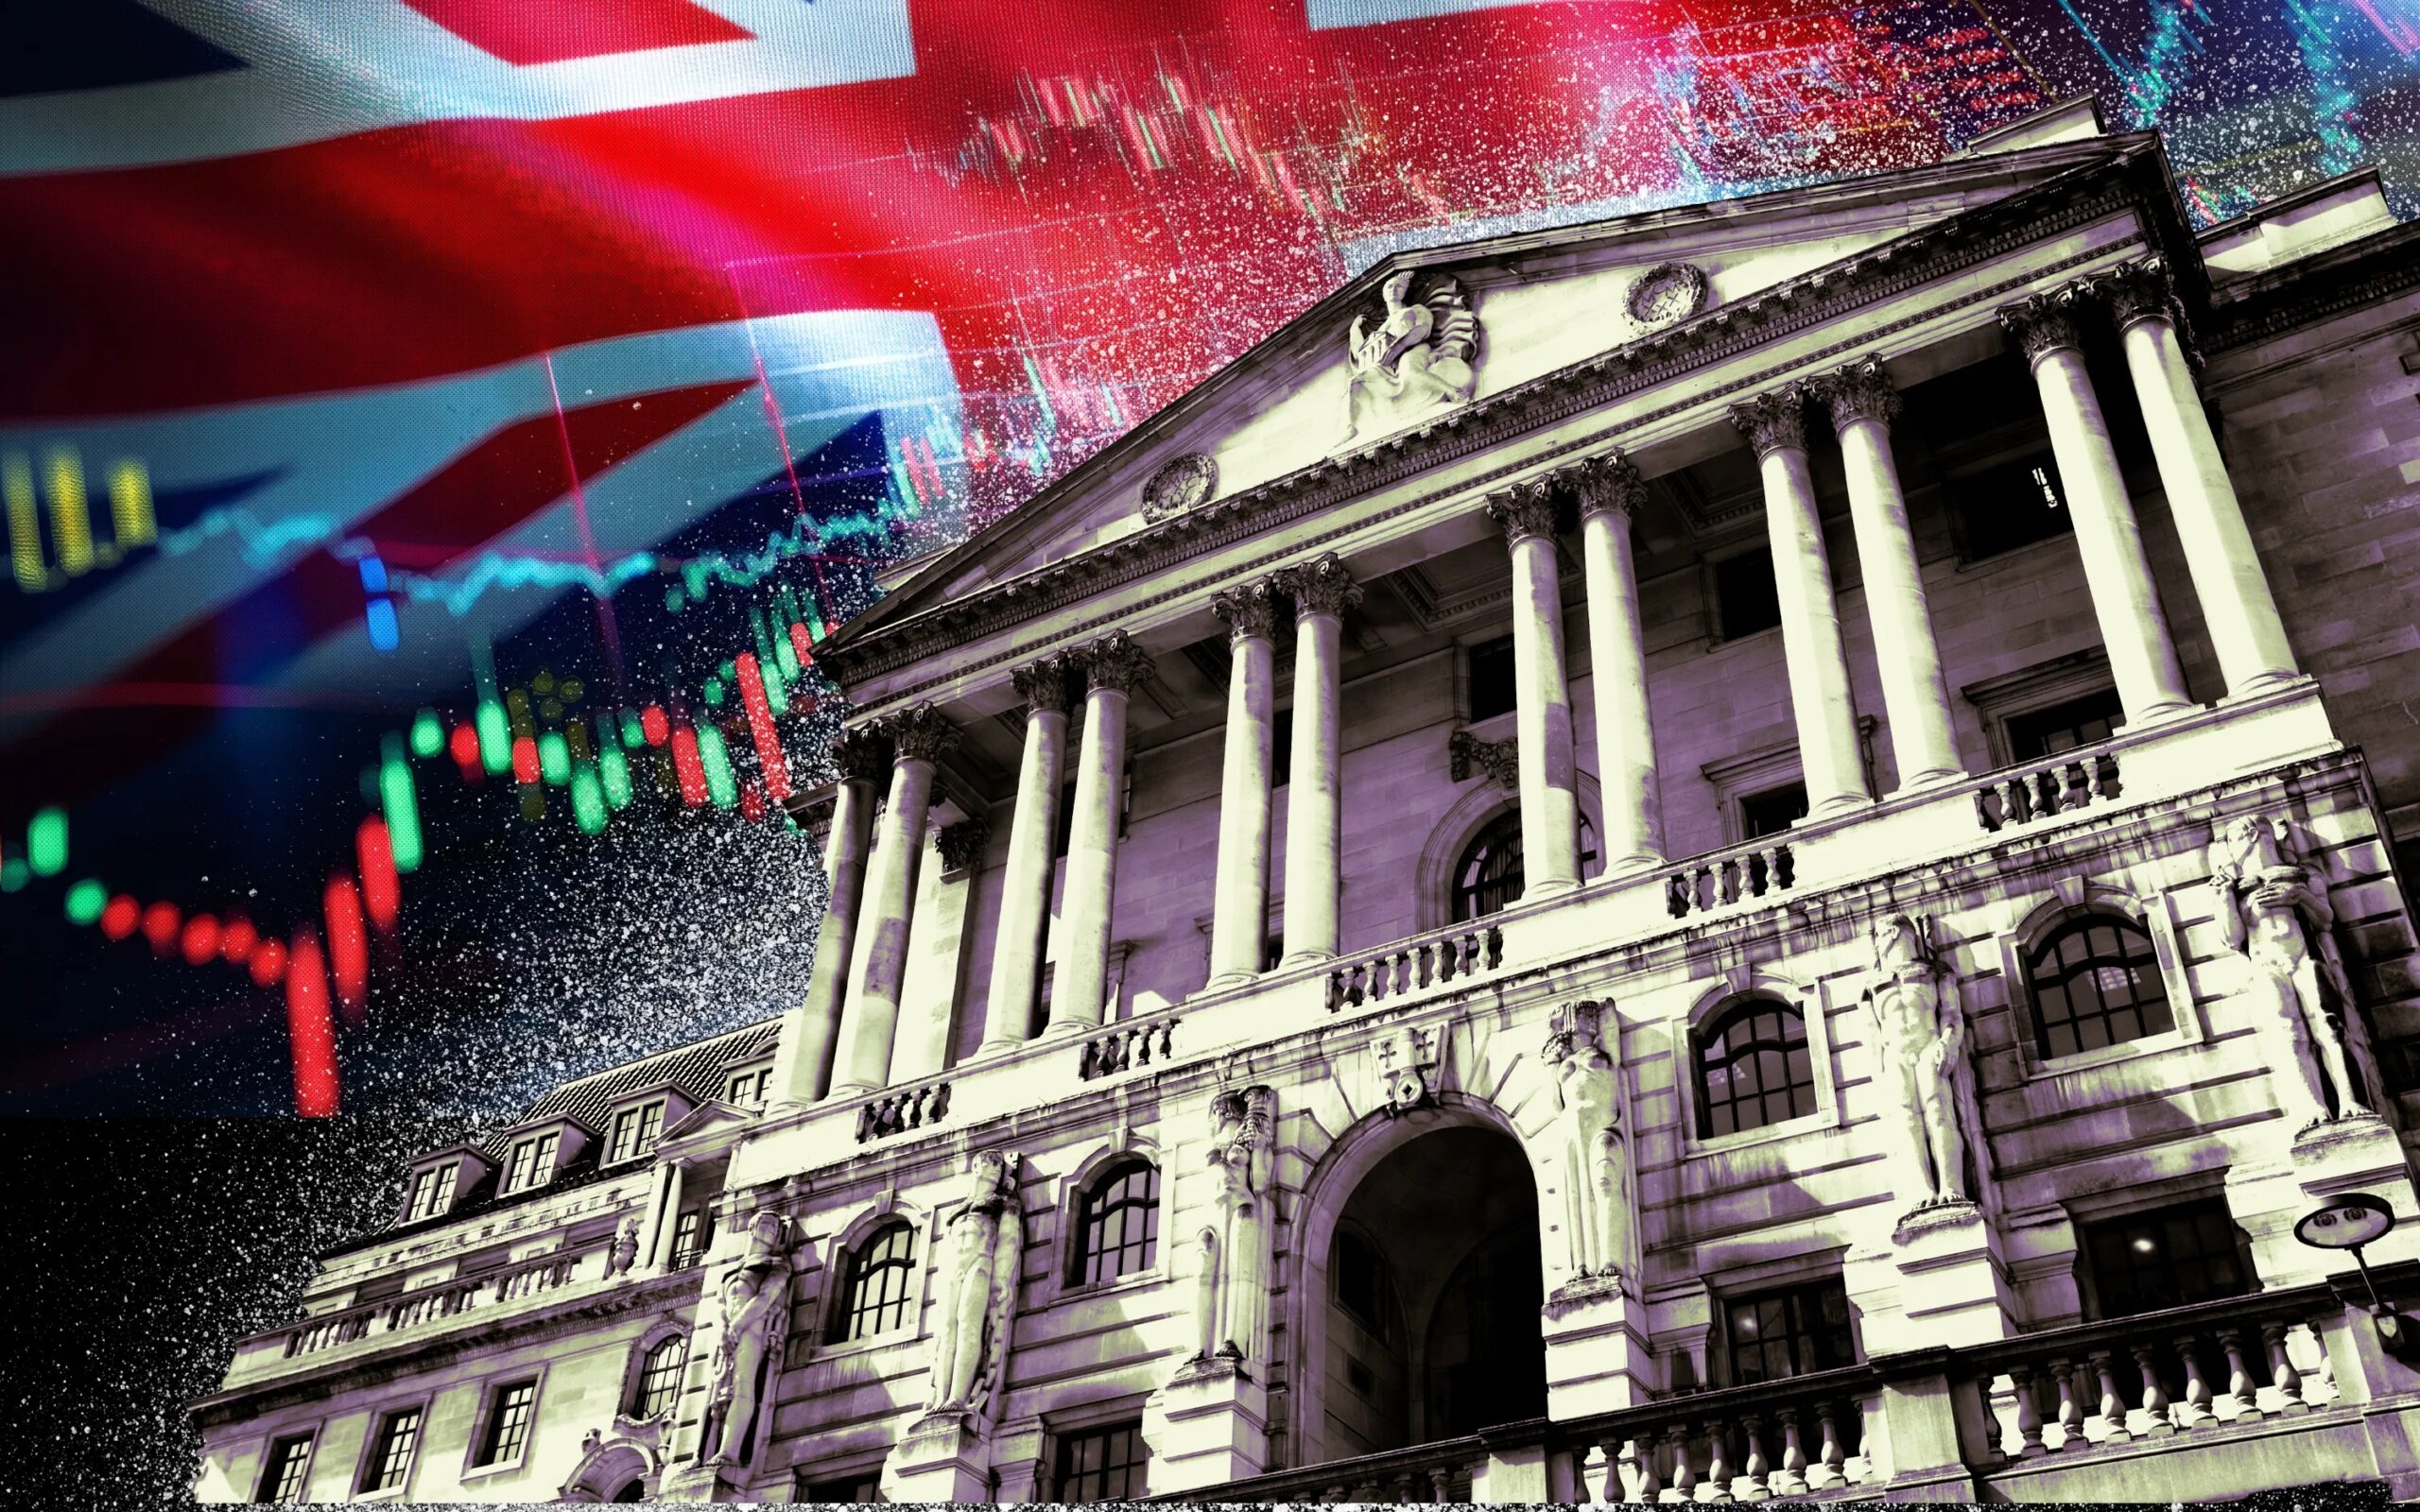
The Bank of England on Thursday cut its key interest rate by a quarter point to four percent, the lowest level in 2.5 years, as it bids to boost a UK economy threatened by US tariffs.

Alongside the expected decision, the BoE forecast British economic growth to hit 1.25 percent this year, slightly better than the central bank’s previous estimate of one percent.

“The direct impact of US tariffs is milder than feared, but more general tariff-related uncertainty still weighs on sentiment,” the BoE said in a statement after studying data gathered by UK businesses.

London and Washington reached an agreement in May to cut levies of more than 10 percent imposed by US President Donald Trump on certain UK-made items imported by the United States, notably vehicles.

The quarter-point cut on Thursday was the BoE’s fifth such reduction since starting a trimming cycle in August 2024.

“Interest rates are still on a downward path, but any future rate cuts will need to be made gradually and carefully,” its governor, Andrew Bailey, said following Thursday’s decision.

The BoE voted 5-4 for the reduction, but not before an unprecedented second vote owing to a three-way split among its nine policymakers that prevented a necessary majority result.

Initially, four members voted for the reduction and four for no change. One member called for a larger cut of 0.50 percent, before switching in favour of a quarter-point drop, as voted for by Bailey.

It was the first time since the BoE became independent of the UK government in 1997 that a second vote had to be held.

See also  Tax revenue hits N27tn after 113% surge – Report

“Looking ahead, interest rates are expected to be 3.5 percent in a year, which is slightly higher than before the (latest) meeting,” noted Kathleen Brooks, research director at XTB trading group.

Expectations that the rate will remain at four percent for longer boosted the British pound.

The BoE’s main task is to keep Britain’s annual inflation rate at 2.0 percent, but the latest official data showed it had jumped unexpectedly to an 18-month high in June.

The Consumer Prices Index increased to 3.6 percent as motor fuel and food prices stayed high.

The BoE on Thursday predicted that the annual inflation rate would peak at four percent next month.

Latest official figures show that Britain’s economy unexpectedly contracted for a second month running in May, and UK unemployment is at a near four-year high of 4.7 percent.

This is largely down to Prime Minister Keir Starmer’s Labour government increasing a UK business tax from April, the same month that the country became subject to Trump’s 10-percent baseline tariff on most goods.

Finance minister Rachel Reeves welcomed the latest rate cut, saying in a statement that it helps to “bring down the cost of mortgages and loans for families and businesses”.

The US Federal Reserve last week kept interest rates unchanged, defying strong political pressure from Trump to slash borrowing costs in a bid to boost the world’s biggest economy.

Asked about US tariffs following the decision, Fed Chair Jerome Powell told a press conference: “We’re still a ways away from seeing where things settle down.”

The European Central Bank is meanwhile widely expected to keep rates unchanged at its next meeting, with eurozone inflation around the ECB’s two-percent target.

See also  Cross-border trading unethical, suppresses Nigerian market — NANTA boss

But that could change, according to some economists, based on how Trump’s tariffs affect the single-currency bloc.

FOLLOW US ON:

FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

TUMBLR

INSTAGRAM


Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Business

US Government Warns American Business Executives About Investing In Nigeria

Published

on

A United States Department of State report has warned American business executives in Nigeria.

The department warned that insecurity, corruption, port inefficiencies, and regulatory uncertainty could significantly hinder investment in Nigeria.

It was reports that the department gave the warning in its 2026 Investment Climate Statements on Nigeria.

The report explained that those challenges continue to weigh on the country’s business environment despite signs of macroeconomic stability.

The department said the country’s investment landscape has been shaped by the outcomes of “painful but necessary” structural reforms introduced by the President Bola Tinubu administration.

The report said the removal of fuel subsidies and liberalisation of the foreign exchange market initially triggered significant economic volatility, although early 2026 indicators suggested some stabilisation.

However, it warned that security concerns, administrative bottlenecks and the social consequences of economic reforms remain significant considerations for foreign investors.

“The security environment is a primary variable which gives pause to potential investors,” the report said.

It noted that although attacks on oil infrastructure in the Niger Delta have decreased, oil theft and illegal bunkering persist.

In the North, the expansion of terrorist and ‘bandit’ groups continues to degrade the climate for agribusiness and mining,” the document added.

The report also raised concerns about how regulators treat foreign business executives in disputes, citing the detention of Tigran Gambaryan, a US citizen and Binance executive, for nearly eight months in 2024.

“Furthermore, the use of coercive exit bans and detentions, highlighted by the high-profile nearly eight-month detention in 2024 of U.S. citizen Binance employee Tigran Gambaryan, serves as a cautionary note for foreign executives regarding the risks of aggressive regulatory friction,” it said.

See also  Fuel imports gulp nearly N1tn amid Dangote-importers feud

The report said such cases could shape perceptions of Nigeria as a destination for foreign investment.

The department identified inefficiencies at Nigerian seaports as another major challenge for businesses, particularly those dependent on imports and exports.

“Port inefficiency remains a significant ‘hidden tax’ on investment,” the report said.

It noted that the Lekki Deep Seaport handled $9.6 billion in trade in 2025 and operated at 50 per cent capacity, helping to ease pressure on older facilities.

FOLLOW US ON:

FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

Nigerian states’ revenues rise 93%, but education spending drops — World Bank

Published

on

The World Bank says Nigeria’s 36 states recorded a 93 per cent increase in revenues between 2023 and 2025 but education received a declining share of the sector’s expenditure.

The bank disclosed this in its latest Nigeria Development Update, which examined how increased public revenues have influenced spending priorities across the federation.

The report was made available to the News Agency of Nigeria by the World Bank in Washington D.C.

According to the report, states’ aggregate revenues rose by approximately 93 per cent in real terms, while expenditure increased by 92 per cent during the period.

The report attributed the improvement partly to exchange-rate reforms, petrol subsidy removal, stronger revenue administration and increased allocations from the federation account.

It said states also benefited from refunds, settlement of longstanding federal obligations, intervention funds, and stronger Value Added Tax collections.

However, education’s share of total state expenditure declined from 14.9 per cent in 2021 to 12.1 per cent in 2025, according to the report.

Health expenditure remained broadly stable at approximately seven per cent, while social protection’s share increased from 1.4 per cent to 4.4 per cent.

The bank said capital expenditure increased significantly, accounting for 61 per cent of state spending, compared with 46 per cent previously.

Transport infrastructure recorded the largest increase, alongside substantial spending on housing, agriculture and other economic investments.

The report quoted Mathew Verghis, the World Bank Country Director for Nigeria, as saying that increased revenues provided the opportunity to improve infrastructure, education, healthcare, and water services.

See also  ‘Travellers suffer fraud as unprofessionalism persists’

He said greater spending efficiency, accountability and improved service delivery were essential to ensuring that additional public resources benefited Nigerians.

The bank acknowledged improvements in states’ fiscal reporting, transparency and internally generated revenue.

It, however, stressed that stronger investment in human capital was necessary to translate economic reforms into sustainable employment and improved living standards.

The report also projected average economic growth of 4.4 per cent between 2026 and 2028, subject to sustained reforms and improved service delivery.

It urged federal and state authorities to ensure that increased public revenues translated into tangible improvements in Nigerians’ welfare.

NAN

Source: punchng.com

FOLLOW US ON:
FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

Nigeria promotes investment without building production capacity – UNILAG don

Published

on

A professor of Comparative Political Economy at the University of Lagos, Adelaja Odukoya, has asserted that Nigeria’s economic policies promote investment without sufficiently strengthening domestic production.

Odukoya argued that the contradiction had weakened the country’s productive foundations, with policies encouraging investment and entrepreneurship while failing to create the technological capacity, productive employment and processing industries needed to drive sustainable development.

Odukoya spoke at the maiden edition of the Adeleke University Toyin Falola Annual Lecture, held on Thursday at the Performing Arts Theatre, Adeleke University, Ede.

The lecture had as its theme, “History, Power and Accumulation: Reimagining Africa in the Globally Disorderly Order.”

Odukoya identified several contradictions in the way the Nigerian state manages economic activity.

He said, “The state promotes investment without creating conditions for technological transfer. It encourages entrepreneurship without generating sufficient productive employment.

“It expands primary-product exports while leaving processing capacity undeveloped. It constructs infrastructure without establishing strong linkages with domestic production.”

According to him, the contradictions explain why increased economic activity and accumulation do not necessarily translate into development.

“Accumulation is not synonymous with development,” Odukoya stated.

He argued that genuine development should be measured by the expansion of productive, technological, institutional and human capabilities.

“A country could attract investment, export minerals and agricultural commodities and record economic activity while still failing to build the domestic industries and technological capabilities required for long-term development,” he said.

His argument was echoed by Prof Toyin Falola, who said Africa’s vast natural resources would continue to reinforce dependency unless governments developed the industrial, technological and institutional capacity to transform them into productive power.

See also  Cross-border trading unethical, suppresses Nigerian market — NANTA boss

Falola said Africa’s resource problem was not simply one of historical exploitation, but also the continent’s failure to convert its resource endowments into power.

“The issue, however, is not just to repeat the history of exploitation. It is more important to know how Africa turns its great resources into power,” Falola said.

He argued that Africa could not afford to remain a spectator as global economic and geopolitical arrangements continued to change, stressing that resource ownership without the capacity to add value would not guarantee influence.

Falola said the continent required a combination of knowledge, government policy and industrial capacity to change its economic position.

“There must be universities that generate new knowledge; there must be governments that translate this knowledge into policies; there must be industries that add value to the continent’s natural resources,” he said.

He added that Africa needed more than improved infrastructure and stronger economies if it wanted to exercise greater influence in the global system.

“The future of the continent will require more than just better infrastructure, improved economies, and more effective political institutions,” Falola said.

Source: punchng.com

FOLLOW US ON:

FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Trending