Connect with us

Business

CBN reveals that Banks shut 476 branches in three years, read details

Published

on

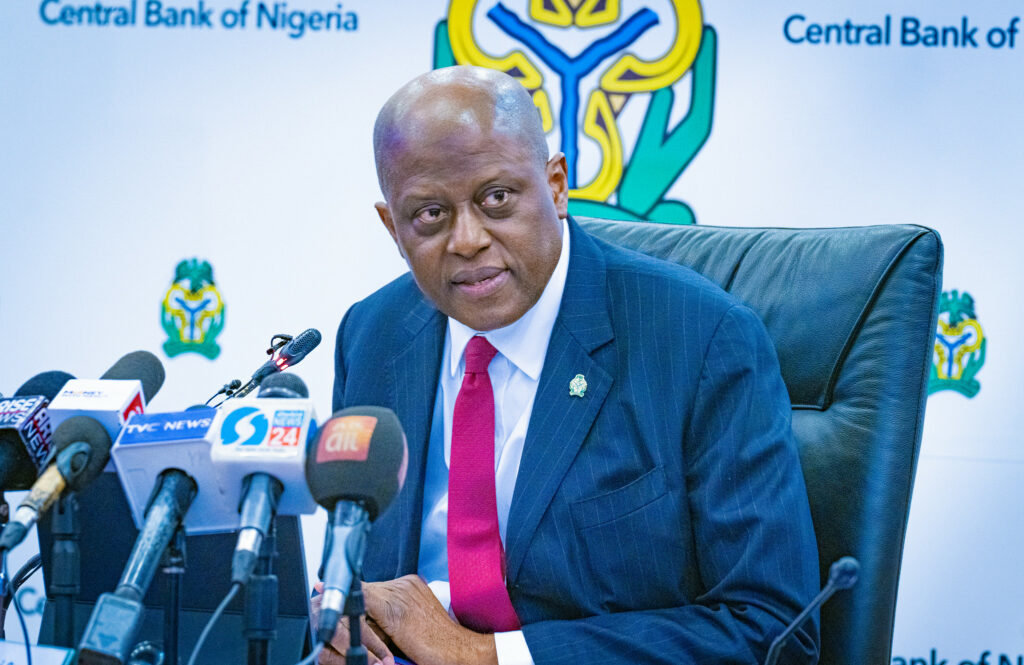
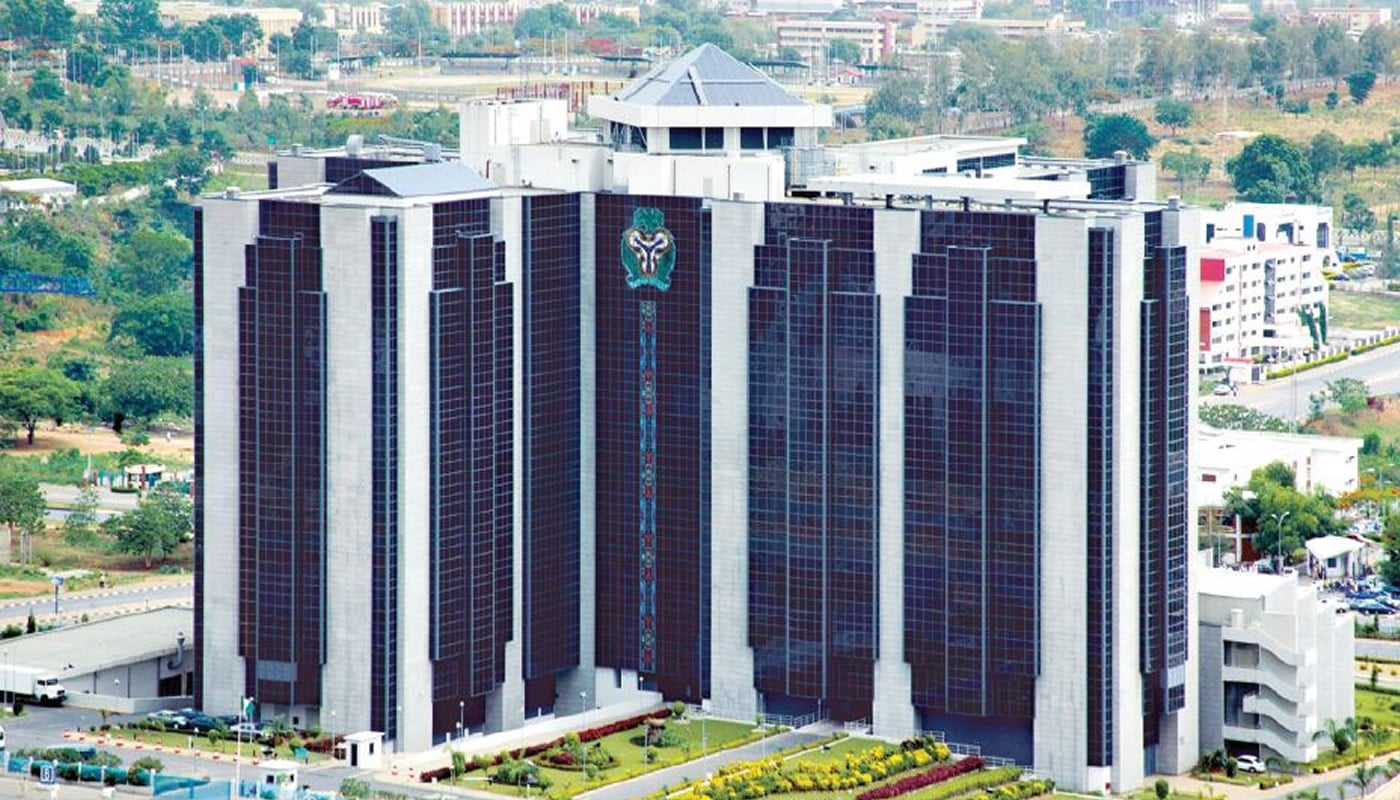
Deposit Money Banks in Nigeria closed a net 476 branches and cash centres between 2022 and 2025, reducing their physical footprint by 8.8 per cent in three years, according to data from the Central Bank of Nigeria.

Figures contained in the CBN’s 2025 Statistical Bulletin for the Financial Sector showed that the number of bank branches and cash centres across the country declined from 5,410 in 2022 to 4,934 in 2025.

The decline occurred despite an increase in the number of banks operating in the country over the period, pointing to a gradual contraction in physical banking locations.

An analysis by The PUNCH showed that the number of branches fell by 37 from 5,410 in 2022 to 5,373 in 2023. The pace of contraction accelerated in the following year, with 229 locations disappearing as the total dropped to 5,144 in 2024. Banks closed another net 210 locations in 2025, bringing the number down to 4,934.

Consequently, about 92 per cent of the 476 net reduction recorded over the three-year period occurred in 2024 and 2025. The CBN explained that the figures cover branches and cash centres operated by commercial, merchant and non-interest banks. The data were sourced from the apex bank and the Nigeria Deposit Insurance Corporation.

The reduction in physical banking locations came even as the number of banks increased from 32 in 2022 to 33 in 2023 and 35 in 2024, before declining slightly to 34 in 2025. The number of branches operated abroad remained unchanged at two throughout the period.

See also  FG blames technical hitch for February salaries delay

A state-by-state analysis showed that Lagos recorded the largest decline in absolute terms. The country’s commercial hub had 1,602 branches and cash centres in 2022, but the figure fell to 1,532 in 2023 and 1,521 in 2024 before dropping further to 1,444 in 2025.

This meant banks closed a net 158 locations in Lagos within three years, representing a 9.9 per cent reduction. The state alone accounted for about one-third of the net decline recorded nationwide.

Despite the reduction, Lagos remained the dominant location for physical banking operations, accounting for about 29 per cent of the country’s 4,934 branches and cash centres in 2025.

The Federal Capital Territory also recorded a decline. The number of locations in Abuja stood at 400 in both 2022 and 2023 before falling to 391 in 2024 and 362 in 2025. This represented a net reduction of 38 branches and cash centres, or 9.5 per cent, over the three-year period.

Ekiti suffered one of the steepest contractions, with its branch network almost halving from 107 locations in 2022 to 57 in 2025, representing a decline of 50 locations or 46.7 per cent.

Enugu followed with a reduction of 44 locations from 162 to 118, while Oyo lost 41, declining from 237 to 196. Other states that recorded sizeable declines included Ondo, where the number fell from 127 to 105; Plateau, from 80 to 61; Osun, from 113 to 96; Cross River, from 83 to 67; and Rivers, from 290 to 275.

The decline was also evident in some of the major commercial centres in northern Nigeria. Kano increased its physical banking locations from 164 in 2022 to 175 in 2023 and 183 in 2024. However, the number fell sharply to 157 in 2025, leaving the state with seven fewer locations than it had three years earlier.

See also  Utomi leads talks with Atiku, Obi on single candidate ahead of 2027, read details

Kaduna followed a similar pattern, rising from 148 locations in 2022 to 156 in 2023 and 164 in 2024 before dropping to 146 in 2025.

Some states, however, recorded an expansion in their banking networks. Delta added 23 locations, with its total increasing from 173 in 2022 to 196 in 2025. Edo also rose from 155 to 165, while Jigawa increased from 31 to 37 and Kogi from 63 to 68.

The data further showed wide disparities in the distribution of physical banking infrastructure across the country. While Lagos alone had 1,444 locations in 2025, Yobe had 23, Taraba 26 and Zamfara 28. Bayelsa and Gombe had 31 each, while Ebonyi recorded 32.

For instance, Lagos alone accounted for more than 29 per cent of all branches and cash centres nationwide in 2025, highlighting the concentration of physical banking infrastructure in the country’s major economic centre.

The latest figures indicate that the contraction in the industry’s physical footprint has accelerated in recent years, underscoring how rapidly banking is migrating from brick-and-mortar to electronic platforms.

The PUNCH recently reported that the Central Bank of Nigeria called for greater adoption of alternative payment channels to expand access to financial services and stimulate economic activity.

Acting Director, Corporate Communications and Investor Relations Department of the CBN, Hakama Sidi-Ali, made the call at the 2026 CBN Fair in Lokoja, Kogi State.

Represented by Zubairu Salihu, Branch Controller of the CBN Lokoja Branch, she said alternative payment channels were particularly important for farmers, traders, small businesses and informal-sector operators who may have limited access to conventional banking services.
Business

DisCos earn N603bn as power offtake drops

Published

on

Electricity distribution companies collected N603.64bn from customers in the second quarter of 2026, despite a decline in the volume of electricity they received from the power market.

The figure was contained in the Nigerian Electricity Regulatory Commission’s second-quarter 2026 report, which showed that the average energy offtake by the DisCos at their trading points fell to 3,197.03 megawatt-hours per hour in the quarter.

The Q2 figure represented a 112.45MWh/h, or 3.40 per cent, decline from the 3,309.48MWh/h average recorded in the first quarter. Despite the decline in offtake, the DisCos recorded an overall offtake performance of 94.07 per cent during the quarter, against available partially contracted capacity of 3,398.41MWh/h.

According to the report, the DisCos received a total of 6,982.32 gigawatt-hours of electricity during the quarter but billed customers for only 5,812.31GWh. It stated, “This translates to an overall energy accounting efficiency of 83.24 per cent and represents a 0.24pp decrease compared to 2026/Q1 (83.48 per cent).”

The report further revealed that the naira value of electricity off-taken by the DisCos stood at N946.57bn, while the total value of energy billed to customers was N744.67bn.

This translated to a billing efficiency of 78.67 per cent, representing a decline of 0.57 percentage points from the 79.24 per cent recorded in the first quarter. At the collection stage, the DisCos recovered N603.64bn from the N744.67bn billed to customers, translating to a collection efficiency of 81.06 per cent.

The report said this represented an improvement of 2.11 percentage points from the 78.95 per cent recorded in Q1. However, the difference between the amount billed and the amount collected stood at N141.03bn during the quarter.

See also  36 states’ budgets jump 47% to N40tn, capital spending falls

The report also disclosed that the weighted average Aggregate Technical, Commercial and Collection losses across the 11 DisCos stood at 36.23 per cent in Q2.

It stated, “The ATC&C loss of 36.23 per cent is 19.31pp higher than the 2026 MYTO target (16.92 per cent) and translates to a cumulative revenue loss of N129.07 billion across all DisCos.”

The 36.23 per cent loss, however, represented a 1.21 percentage-point improvement from the 37.44 per cent recorded in Q1.

The report noted that all the DisCos failed to meet their ATC&C targets during the quarter, with “Kaduna DisCo recording the worst underperformance relative to the target (Actual – 67.70 per cent vs target – 18.18 per cent),” it stated.

On market obligations, the report said the cumulative upstream invoice payable by the DisCos stood at N410.38bn in Q2.

The amount comprised N326.46bn for generation costs from the Nigerian Bulk Electricity Trading Company and N83.92bn for transmission and administrative services provided by the market operator.

The DisCos collectively remitted N385.44bn, comprising N306.62bn to NBET and N78.82bn to the market operator, leaving an outstanding balance of N24.94bn. This represented a market remittance performance of 93.92 per cent, slightly lower than the 94.08 per cent recorded in Q1.

The report added that the Federal Government had taken responsibility for about 50 per cent, or N321.26bn, of the total generation costs through subsidies arising from the freezing of end-use customer tariffs at the rates applicable in July 2024.

Meanwhile, three international bilateral customers purchasing electricity from grid-connected generating companies paid $8.67m against an $18.84m invoice issued by the market operator during the quarter.

See also  EU, Germany, Nigeria unveil €18.3m project to boost agriculture, job

This represented a remittance rate of 46.02 per cent. Domestic bilateral customers, on the other hand, paid N6.91bn against an invoice of N7.55bn, representing a remittance rate of 91.54 per cent.

Source: punchng.com

FOLLOW US ON:

FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

Personal loans rise to N2tn as Nigerians borrow more

Published

on

Personal loans obtained by Nigerians rose to an estimated N2.06tn in May 2026, as consumer credit continued to expand amid persistent cost pressures and weak consumer spending, according to the latest Economic Report of the Central Bank of Nigeria.

The figure, calculated from data contained in the CBN’s May 2026 Economic Report, represents about 64.78 per cent of the N3.18tn total consumer credit outstanding during the month. The report covers developments in the real, fiscal, financial and external sectors of the economy.

The apex bank said consumer credit increased by 1.60 per cent from N3.13tn in April to N3.18tn in May, indicating that Nigerians borrowed an additional N50bn within one month.

It said, “Consumer credit outstanding increased by 1.60 per cent to N3.18tn from N3.13tn in the preceding month, driven by growth in personal and retail loans, which rose by 1.98 and 0.90 per cent, respectively.”

The CBN added, “Personal loans remained the dominant component of consumer credit, accounting for 64.78 per cent, while retail loans constituted 35.22 per cent.”

Based on the proportions reported by the apex bank, personal loans stood at approximately N2.06tn at the end of May, while retail loans amounted to about N1.12tn.

The 1.98 per cent month-on-month increase in personal loans suggests that the balance rose by roughly N40bn during the period. Retail loans, which include credit tied more directly to the purchase of goods and services, recorded a slower increase of 0.90 per cent.

The figures show that personal borrowing remained the main driver of Nigeria’s consumer-credit market, accounting for nearly two-thirds of outstanding credit.

See also  FG offers land to investors for mass housing projects

The increase came against a challenging operating environment for households and businesses. The CBN reported that economic activity remained weak in May, with its composite Purchasing Managers’ Index at 49.60 points, slightly higher than 49.40 points in April but still below the 50-point threshold separating expansion from contraction.

According to the bank, the contraction reflected subdued demand, declining new orders and elevated production costs. It also identified weak consumer spending and higher energy-related costs as pressures on the industry and services sectors.

Inflation also remained elevated during the period. Headline inflation increased to 15.93 per cent in May from 15.69 per cent in April, which the CBN attributed to persistent cost pressures and higher energy prices. However, month-on-month inflation slowed to 1.75 per cent from 2.13 per cent.

The combination of rising consumer credit and weak consumer spending suggests that households were increasingly accessing credit at a time when living and operating costs remained under pressure.

A recent report Enhancing Financial Inclusion & Advancement noted that four in every 10 Nigerians borrowing from formal financial institutions now take loans mainly for consumption and coping needs, as rising financial pressures increasingly push credit away from productive activities.

The 2026 Access to Financial Services in Nigeria Survey revealed that 40.8 per cent of formal borrowers used loans for coping and consumption, up sharply from 31.7 per cent in 2023.

The 9.1 percentage-point increase made coping and consumption the largest purpose of formal credit, overtaking productive enterprise borrowing, which fell from 40.2 per cent to 34.3 per cent during the same period.

See also  Recapitalised banks poised to drive Nigeria’s $1trn economy ambition

Borrowing for household assets also declined from 25.2 per cent to 23.4 per cent. The report warned, “Coping/consumption purposes rose from 31.7 per cent to 40.8 per cent; productive purpose fell from 40.2 per cent to 34.3 per cent. We need to ensure that credit builds productive capacity and does not produce distress.”

Formal credit use increased from six per cent of adults in 2023 to 10 per cent in 2026, with about 11.9 million Nigerians borrowing from regulated providers. When informal sources were included, 36 per cent of adults had access to some form of credit.

Credit use among informally employed Nigerians tripled from five per cent to 15 per cent, while borrowing among people aged 18 to 35 rose from four per cent to 10 per cent. Business owners recorded an increase from four per cent to 10 per cent, while farmers rose from two per cent to six per cent.

However, the report found significant distress among borrowers. About 45.8 per cent of formal-credit users reported some or serious repayment stress, while 83.8 per cent experienced ongoing financial stress.

Source: punchng.com

FOLLOW US ON:

FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

NAFDAC seizes N300m banned drinks in Lagos

Published

on

The National Agency for Food and Drug Administration and Control has seized alcoholic beverages worth an estimated N300m packaged in sachets and PET bottles below 200ml during enforcement operations in Lagos State.

NAFDAC disclosed this in a statement shared on its Facebook page on Sunday, adding that some distributors and retailers involved in the sale of the prohibited products were arrested.

The agency said the enforcement operations were carried out at Ile-Epo Market, Ojuwoye Market in Mushin and Oke-Arin Market on Lagos Island.

“Officials evacuated several cartons of alcoholic beverages packaged in sachets and PET bottles below 200ml from these locations.

“Distributors and retailers were arrested during operations at Ile-Epo Market, while raids were also conducted at Ojuwoye Market, Mushin, and Oke-Arin Market, Lagos Island,” the statement said.

NAFDAC said investigations revealed that some distributors and retailers were hoarding the prohibited products amid increased demand and rising prices.
The agency said the enforcement was part of efforts to ensure compliance with the ban on the sale and distribution of alcoholic beverages packaged in sachets and PET bottles below 200ml.

It warned distributors, retailers and other operators against selling, distributing or hoarding the prohibited products.

“NAFDAC emphasises that the ban remains in force and warns distributors, retailers and other operators against the sale, distribution or hoarding of the prohibited products.

“The value of the seized products is estimated at N300m,” it stated.

PUNCH Metro reported on August 25 that NAFDAC ordered manufacturers of banned alcoholic beverages packaged in sachets and polyethylene terephthalate bottles below 200ml to recall the products nationwide or risk closure of their facilities.

See also  Drivers, cooks, traders can own refinery shares, says Dangote

NAFDAC had also vowed to fully enforce the Federal Government-approved prohibition of alcoholic beverages packaged in sachets and PET or plastic bottles below 200ml, warning that the ban was irrevocable.

The agency had stated that the years of grace given to manufacturers by the Federal Government to stop producing the products had expired.

Source: punchng.com

FOLLOW US ON:

FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Trending