Connect with us

Business

FG disputes World Bank’s N7.7tn interest payments, read details

Published

on

The Federal Government has faulted the World Bank’s assessment of Nigeria’s debt position, dismissing concerns that interest payments of N7.7tn in the first half of 2026 threaten the country’s debt sustainability.

The Federal Ministry of Finance described reports that interest payments amounted to 124 per cent of Federal Government revenue during the period as misleading, arguing that the calculation relied on incomplete revenue figures and included debt obligations serviced on behalf of state governments.

The ministry stated its position in a statement issued on Sunday and shared on X by the Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele.

According to the ministry, Nigeria’s fiscal position had improved, with revenue growing faster than interest payments.

It said, “The Federal Ministry of Finance has noted recent analysis and public commentary which, citing the World Bank’s October 2026 Nigeria Development Update, claims that Federal Government interest payments reached 124 per cent of revenue in the first half of 2026. This conclusion is misleading, for three reasons.”

The response followed reports based on the World Bank’s October 2026 Nigeria Development Update, which put Federal Government revenue at N6.2tn and interest payments at N7.7tn in the first half of the year.

An analysis of the published figures by The PUNCH showed that interest payments represented approximately 124.2 per cent of revenue, exceeding revenue by N1.5tn. The ratio was calculated from the figures published by the World Bank and was not expressly stated in the report.

However, the ministry argued that the calculation compared obligations covering multiple tiers of government with revenue attributed solely to the Federal Government.

“The interest figure includes debt the Federal Government services on behalf of other tiers of government, including external loans to states. Measuring this against federal revenue alone overstates the ratio, which is only meaningful when debt and revenue cover the same level of government,” it said.

The ministry also argued that the revenue figure excluded income earned by government agencies and enterprises but not yet remitted to the Treasury.

It added that statutory payment schedules meant some taxes were collected predominantly in the second half of the year, making first-half revenue an incomplete basis for assessing annual debt obligations.

According to the ministry, the interest-to-revenue ratio stood at 156 per cent in the first half of 2025, compared with approximately 124 per cent in the corresponding period of 2026.

It said the full-year debt-service-to-revenue ratio had fallen below 60 per cent, compared with 97 per cent before the current administration’s reforms, describing the reduction as evidence of improved fiscal management.

The ministry further stated that Federal Government revenue rose by 72 per cent, from N3.6tn in the first half of 2025 to N6.2tn in the corresponding period of 2026, while interest payments increased by 38 per cent, from N5.6tn to N7.7tn.

See also  Tinubu, Shell in high-level talks over S20bn Nigeria investment

Consequently, it said, the interest-to-revenue ratio declined by about 32 percentage points, while the gap between interest payments and revenue narrowed from N2tn to N1.5tn.

“This is the result of reforms working, not a sign of fiscal distress,” the ministry declared.

It also rejected the use of a six-month fiscal snapshot as a definitive measure of debt sustainability, arguing that full-year projections provided a more appropriate assessment.

“The same World Bank report projects Nigeria’s full-year 2026 debt service, covering both interest and principal, at 46 per cent of revenue. This is the appropriate benchmark, and a guide to avoid the invalid conclusions being drawn,” the statement read.

The ministry also defended the Federal Government’s borrowing programme, insisting that all loans obtained by the current administration were lawful and duly approved.

It maintained that every naira borrowed fell within the limits authorised by the National Assembly under the 2026 Appropriation Act and the approved borrowing plan.

According to the statement, government borrowing complied with the Fiscal Responsibility Act 2007 and the Debt Management Office (Establishment) Act 2003, while details of the country’s debt obligations were regularly published by the Debt Management Office.

However, despite challenging the World Bank’s assessment and questioning the basis of the interest-to-revenue calculation, the ministry did not provide revised revenue and interest-payment figures or an alternative ratio to substantiate its position.

W’Bank’s $1.25bn loan

Meanwhile, the Federal Government will begin repaying the principal on a $1.25bn World Bank loan in December 2031, with the final instalment on one of the facilities due in June 2060, according to financing agreements reviewed by The PUNCH.

The facility, secured under the Nigeria Actions for Investment and Jobs Acceleration Development Policy Financing programme, is intended to support reforms aimed at expanding access to credit, improving electricity supply, strengthening trade competitiveness and increasing government revenue.

The PUNCH reported in July 2026 that the World Bank had approved the $1.25bn facility amid public concerns over Nigeria’s rising debt burden and calls for the Federal Government to reduce external borrowing.

In an earlier statement, the Washington-based bank said it had approved the Nigeria Actions for Investment and Jobs Acceleration Development Policy Financing operation to support Nigeria’s transition towards a more inclusive growth model that would stimulate growth and create jobs.

The bank said the operation would support reforms to strengthen the foundations for growth and competitiveness.

“These include deepening capital markets, modernising the regulatory framework for the digital economy and e-governance, advancing power sector reforms to accelerate electrification, lowering trade barriers in line with Nigeria’s ECOWAS and AfCFTA commitments to help ease price pressures, improving access to quality agricultural seeds, and strengthening domestic revenue mobilisation,” the statement added.

The loan was the second-largest single World Bank facility secured by Nigeria under President Bola Tinubu, after the $1.5bn Reforms for Economic Stabilisation to Enable Transformation Development Policy Financing approved in June 2024.

See also  Troops kill 274 insurgents as Nigeria records 882 attacks

Documents reviewed by The PUNCH showed that the $1.25bn financing comprises a $750m concessional credit from the International Development Association and a $500m loan from the International Bank for Reconstruction and Development, both institutions of the World Bank Group.

Differing repayment periods

Principal repayments on both facilities will begin on December 15, 2031, but their maturity dates differ. The IDA credit is scheduled to be fully repaid by June 2051, while the IBRD loan runs until June 2060.

The IDA provides concessional financing to low-income countries on more favourable terms, while the IBRD lends primarily to middle-income and creditworthy lower-income countries on market-linked terms.

The agreements were signed on behalf of Nigeria by the Minister of Finance, Taiwo Oyedele, on October 6, 2026, while the World Bank’s Country Director, Mathew Verghis, signed on June 30, 2026.

According to Schedule 2 of the IDA financing agreement, Nigeria will repay 2.5 per cent of the $750m credit every six months, beginning on December 15, 2031, and ending on June 15, 2051.

This amounts to $18.75m in principal repayments every six months, or $37.5m annually during full repayment years, excluding interest and other applicable charges.

For the $500m IBRD facility, the repayment schedule provides for semi-annual principal instalments of 1.72 per cent from December 15, 2031, through December 15, 2059, followed by a final instalment of 1.96 per cent on June 15, 2060.

The regular instalments amount to approximately $8.6m every six months, while the final principal payment is about $9.8m.

Combined, the facilities will require principal repayments of approximately $27.35m every six months between December 2031 and June 2051, equivalent to $54.7m annually during full repayment years.

The repayment obligations will extend across several administrations, with the final principal payment on the IBRD facility falling due nearly 34 years after the agreements were signed.

The schedules cover principal repayments only and do not represent the total cost of borrowing, which will also include interest and applicable charges.

Under the IBRD agreement, the interest rate is determined by the reference rate plus a variable spread. The IDA credit carries an interest charge calculated using the reference rate plus a variable spread, less 250 basis points.

The IDA agreement states, “The Interest Charge is the Reference Rate plus the Variable Spread minus 250 basis points,” subject to applicable rate limits and possible conversions.

The IBRD loan also attracts a front-end fee of 0.25 per cent, equivalent to $1.25m, as well as an annual commitment charge of 0.25 per cent on the undisbursed balance.

For the IDA credit, the agreement provides for a maximum annual commitment charge of 0.5 per cent on the undisbursed financing balance.

The documents do not specify a fixed dollar amount for total interest payments over the repayment period. The eventual borrowing cost will therefore depend on the applicable rates and other contractual provisions.

See also  Cooking gas prices ease as supply improves

The $750m IDA credit is structured for disbursement in a single tranche, subject to the World Bank’s assessment of Nigeria’s economic policies and implementation of the agreed reforms.

The $500m IBRD facility is divided into two withdrawal tranches of $249.375m each, with the remaining $1.25m allocated to the front-end fee.

Release of the second tranche depends on satisfactory progress in implementing the programme, maintaining an adequate macroeconomic framework and completing agreed policy actions.

Under the IBRD agreement, if the government fails to take satisfactory corrective measures within 90 days of receiving notice from the bank, the lender may cancel part or all of the undisbursed balance.

Both agreements have a closing date of December 31, 2027.

Areas of reforms

The agreements identify two broad areas of reform: improving access to financial credit, digital services and electricity, and strengthening competitiveness through trade, taxation and agricultural reforms.

Among the measures recognised are the Investment and Securities Act 2025, the National Integrated Electricity Policy, electricity metering reforms and regulations facilitating private investment in interconnected mini-grids.

The government also committed to implementing trade reforms under the African Continental Free Trade Area, including the gradual liberalisation of 90 per cent of tariffs on goods from African countries over 10 years.

Other measures include removing import bans on specified essential food products and inputs, reducing import adjustment taxes on selected commodities by at least 25 per cent in 2026, and progressively eliminating applicable adjustment taxes between 2027 and 2036.

On taxation, the agreements recognise the introduction of mandatory electronic invoicing for Value Added Tax, a 15 per cent minimum effective tax rate for large companies and multinational enterprises, and an increase in the maximum personal income tax rate from 24 to 25 per cent.

The financing arrangements also impose reporting and accountability requirements on the government.

Nigeria is required to maintain dedicated dollar accounts for receiving the proceeds and ensure that equivalent amounts are reflected in its budget management system.

The Federal Ministry of Finance must report the amounts received, relevant account details and records of transactions to the World Bank within 30 days of each withdrawal

The agreements also require the accounts to be audited by auditors of the Central Bank of Nigeria acceptable to the World Bank. Certified audit reports must be submitted within four months of withdrawal and made publicly available.

The financing is intended to support Nigeria’s economic reform programme, with disbursement conditional on satisfactory implementation of the agreed measures and maintenance of an adequate macroeconomic policy framework.

Source: punchng.com

FOLLOW US ON:
FACEBOOK

WHATSAPP CHANNEL

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Business

Revenue boom: World Bank faults states’ spending priorities, read full details

Published

on

The World Bank has criticised the spending priorities of Nigerian state governments, warning that increased revenues following recent economic reforms have not translated into proportionate investments in education, healthcare and social protection.

The global lender observed that although states had increased spending on essential public services, investments in transport infrastructure had grown considerably faster, even in states with poor human development indicators.

A Senior Economist at the World Bank Nigeria Office, Gloria Joseph-Raji, raised the concerns on Tuesday in Abuja during the launch of BudgIT’s 2026 State of States Report, themed ‘From Allocation to Impact: Rethinking State Spending Priorities.’

She said, “Spending on education, health, and social protection has also risen substantially, but it has not kept pace with the rapid growth in transport infrastructure spending, even in states with weaker human capital outcomes.”

Joseph-Raji explained that the bank’s October Nigeria Development Update, which examined budget implementation reports from all 36 states, found that governments had expanded transport infrastructure and reduced their debt burdens, particularly domestic debt, following increased fiscal allocations.

She attributed the revenue growth to petrol subsidy removal, exchange rate unification and improvements in tax administration since 2023, alongside federal intervention funds and the settlement of longstanding obligations to states.

According to her, the additional resources have enabled states to meet salary obligations and created opportunities for improved public service delivery.

However, she warned that excessive dependence on Federation Account allocations continued to expose state finances to fluctuations in federally shared revenue.

“In 2025, federation transfers accounted for more than three-quarters of revenue in all but a handful of states,” she said.

See also  Miners reject governors’ six-month mining ban plan

She disclosed that federation transfers accounted for 73 per cent of aggregate state revenues between 2021 and 2025, excluding Lagos, while internally generated revenue was sufficient to cover recurrent expenditure in only two states.

Joseph-Raji noted that states received 26.72 per cent of net Federation Account revenues and now received 55 per cent of Value Added Tax revenue under the revised sharing formula.

Meanwhile, BudgIT’s Country Director, Vahyala Kwaga, disclosed that aggregate revenue across the 34 states covered in its comparative analysis rose from N4.99tn in 2022 to N15.53tn in 2025, representing an increase of N10.54tn.

He said FAAC allocations increased by more than 232 per cent, from N3.43tn to N11.38tn during the period.

Despite the revenue growth, Kwaga disclosed that the states had spent only N8.60tn, representing 24.4 per cent of their combined N35.22tn approved budgets, by June 2026.

“We must also examine how effectively they deploy the resources available to them, what they prioritise and whether their spending is delivering the outcomes that citizens need,” he said.

He explained that BudgIT had revised its assessment methodology to place greater emphasis on spending in education, healthcare, agriculture, water and sanitation, alongside revenue performance and debt sustainability.

Presenting the report, BudgIT’s Head of Research and Policy Advisory, Adejoke Akinbode, disclosed that total debt across the 35 states assessed increased by 10.41 per cent, from N10.57tn in 2024 to N11.67tn in 2025.

She identified Lagos as the most indebted state, with N2.9tn, while Osun spent N100.17bn servicing debt, equivalent to 28.6 per cent of its revenue.

See also  Troops kill 274 insurgents as Nigeria records 882 attacks

Akinbode said Lagos ranked first in overall fiscal sustainability, followed by Enugu, Bayelsa, Delta and Kebbi, while Cross River ranked last. Rivers was excluded because of inadequate fiscal data.

She urged states to reduce administrative costs, strengthen revenue collection and link borrowing to productive investments.

In her keynote address, an economist and lecturer at Amadeus University, Abia State, Dr Iboro Nelson, argued that rising government revenues had failed to compensate households for the economic hardship associated with recent reforms.

She disclosed that states collectively budgeted N1.32tn for healthcare in 2024 but spent N816.64bn, while education expenditure stood at N1.61tn against N2.41tn budgeted.

According to her, average annual spending per resident amounted to N3,483 on healthcare and N6,981 on education, equivalent to approximately N290 and N582 monthly, respectively.

“This is actually not fiscal space, but fiscal illusion,” she said.

Nelson blamed weak budget implementation, unrealistic expenditure projections, overlapping projects and excessive recurrent costs for the limited developmental impact of rising allocations.

Also speaking, a Programme Manager at the Ford Foundation’s West Africa Office, Joy Ehinor-Esezobor, urged governments to measure fiscal success by improvements in citizens’ lives rather than revenue growth or rankings.

“The ultimate measure of success should not simply be a better fiscal ranking, but better services and improved living conditions,” she said.

The programme is seeking to establish a framework for developing Nigeria’s underutilised small hydropower resources through private investment and public-private partnerships.

Source: punchng.com

FOLLOW US ON:

FACEBOOK

WHATSAPP CHANNEL

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

Otti woos US investors to Abia

Published

on

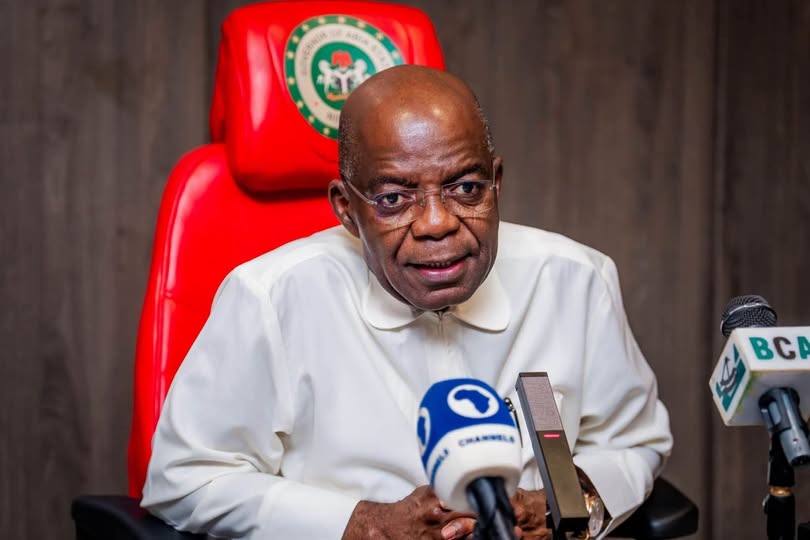
Governor Alex Otti of Abia State has concluded plans to bring investors, business leaders, policymakers, development partners, diplomatic representatives and entrepreneurs to the state to explore investment opportunities and strengthen commercial relations between Africa and the United States.

In a statement he signed and issued to newsmen on Sunday, the Chief of Staff to the Governor, Pastor Caleb Ajagba, disclosed that the Abia State Government had unveiled plans to attract American and other international investors to the state through the 2026 edition of the African Diaspora Conference and Expo, AFRICANDO, scheduled for this month.

Ajagba said, “AFRICANDO is a platform for translating international economic engagement into concrete investments and commercial partnerships. The state government is working with the organisers to ensure that the conference goes beyond speeches and networking to facilitate transactions, business agreements and sustainable investment.”

According to him, the 2026 edition, with the theme, “Deepening U.S.–Africa Commercial Ties in the Era of AfCFTA,” would connect investment opportunities in Abia and other African markets with American capital, technology, expertise and international distribution networks.

He added, “The African Continental Free Trade Area, AfCFTA, presents opportunities for African businesses to expand beyond their domestic markets, while international partnerships could help them improve production capacity and competitiveness.

“Abia is strategically positioned to benefit from the initiative because of its manufacturing and entrepreneurial base, particularly in Aba, which is known for indigenous manufacturing, commerce and craftsmanship.”

Ajagba added that Otti’s administration “is investing in infrastructure, strengthening public institutions and improving the business environment to position the state as a destination for private investment.”

See also  Ondo crash: NAF sets up probe, FG plans safety reforms

He explained that international delegates and prospective investors would be encouraged not only to attend conference sessions but also to visit strategic economic locations, manufacturing clusters, enterprises and government-backed projects to assess investment opportunities firsthand.

He said the approach was intended to give participants a practical understanding of the state’s economic potential and create opportunities for direct engagement with local businesses and relevant government agencies.

“AFRICANDO 2026 is not exclusively an Abia event. It is an international economic platform being hosted in Abia State,” he continued.

He listed agriculture and agro-processing, manufacturing, consumer goods, energy, financial services, healthcare, transportation and logistics, science and technology, artificial intelligence and emerging technologies among the sectors expected to receive attention.

A major feature of the conference, he said, would be a structured Deal Room and Investment Marketplace, where investment-ready projects from Abia and participating businesses would be presented to prospective investors.

Source: punchng.com

FOLLOW US ON:
FACEBOOK

WHATSAPP CHANNEL

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

Personal loans hit new high N1.99tn

Published

on

Nigerians’ outstanding personal loans increased by an estimated N58.5bn in the second quarter of 2026, reaching N1.99tn at the end of June, as households faced persistent inflationary pressures and high borrowing costs.

An analysis by The PUNCH of the Central Bank of Nigeria’s Second Quarter 2026 Economic Report showed that personal loans rose by 3.03 per cent from approximately N1.93tn recorded at the end of March.

The development came as total consumer credit increased by 3.26 per cent to N3.17tn from N3.07tn in the preceding quarter, representing an increase of about N100bn within three months.

The CBN stated, “Consumer credit outstanding increased by 3.26 per cent to N3.17tn, from N3.07tn in the preceding quarter. The increase reflected growth in both retail and personal loans, which rose by 4.10 per cent and 3.03 per cent, respectively.”

According to the report, personal loans accounted for 62.87 per cent of total consumer credit, while retail loans constituted the remaining 37.13 per cent.

This means that nearly N63 out of every N100 owed by consumers to financial institutions was classified as personal borrowing, highlighting its dominance in the consumer credit market.

Retail loans also increased by approximately N46.5bn to N1.18tn at the end of June, compared with an estimated N1.13tn in March, representing quarterly growth of 4.10 per cent.

Although retail loans recorded a faster percentage increase, personal loans contributed more to the outstanding stock of consumer credit.

The increase in personal borrowing occurred amid renewed inflationary pressures, which continued to affect household purchasing power.

See also  FG backs DHQ as coup rumour sparks political firestorm

The CBN reported that headline inflation rose to 15.91 per cent in June 2026 from 15.38 per cent in March, reflecting increases in the prices of essential goods and services.

The report attributed the development largely to higher energy and commodity prices associated with geopolitical tensions in the Middle East, which increased production and transportation costs.

These conditions placed additional pressure on household expenditure, particularly for consumers whose incomes had not increased sufficiently to offset rising prices.

However, the report did not establish whether the increase in personal loans was driven primarily by household financial difficulties, consumption needs or improved access to credit.

The growth in consumer borrowing also occurred despite elevated lending rates in the banking sector.


According to the CBN, the average prime lending rate declined marginally to 19.01 per cent in Q2 from 19.37 per cent in the preceding quarter.

In contrast, the maximum lending rate increased slightly to 34.37 per cent from 34.34 per cent, indicating that borrowing remained expensive for some categories of bank customers.

Although these rates reflect broader banking sector lending conditions rather than specific personal loan charges, they provide an indication of the financing environment confronting borrowers.

A recent report ‘Enhancing Financial Inclusion & Advancement’ noted that four in every 10 Nigerians borrowing from formal financial institutions now take loans mainly for consumption and coping needs, as rising financial pressures increasingly push credit away from productive activities.

The ‘2026 Access to Financial Services in Nigeria Survey’ revealed that 40.8 per cent of formal borrowers used loans for coping and consumption, up sharply from 31.7 per cent in 2023.

See also  Troops kill 274 insurgents as Nigeria records 882 attacks

The 9.1 percentage-point increase made coping and consumption the largest purpose of formal credit, overtaking productive enterprise borrowing, which fell from 40.2 per cent to 34.3 per cent during the same period.

Borrowing for household assets also declined from 25.2 per cent to 23.4 per cent. The report warned, “Coping/consumption purposes rose from 31.7 per cent to 40.8 per cent; productive purpose fell from 40.2 per cent to 34.3 per cent. We need to ensure that credit builds productive capacity and does not produce distress.”

Formal credit use increased from six per cent of adults in 2023 to 10 per cent in 2026, with about 11.9 million Nigerians borrowing from regulated providers. When informal sources were included, 36 per cent of adults had access to some form of credit.

Credit use among informally employed Nigerians tripled from five per cent to 15 per cent, while borrowing among people aged 18 to 35 rose from four per cent to 10 per cent. Business owners recorded an increase from four per cent to 10 per cent, while farmers rose from two per cent to six per cent.

Source: punchng.com

FOLLOW US ON:

FACEBOOK

WHATSAPP CHANNEL

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Trending