Connect with us

Business

IMF lists four priorities for Nigeria as Stablecoin use surges

Published

on

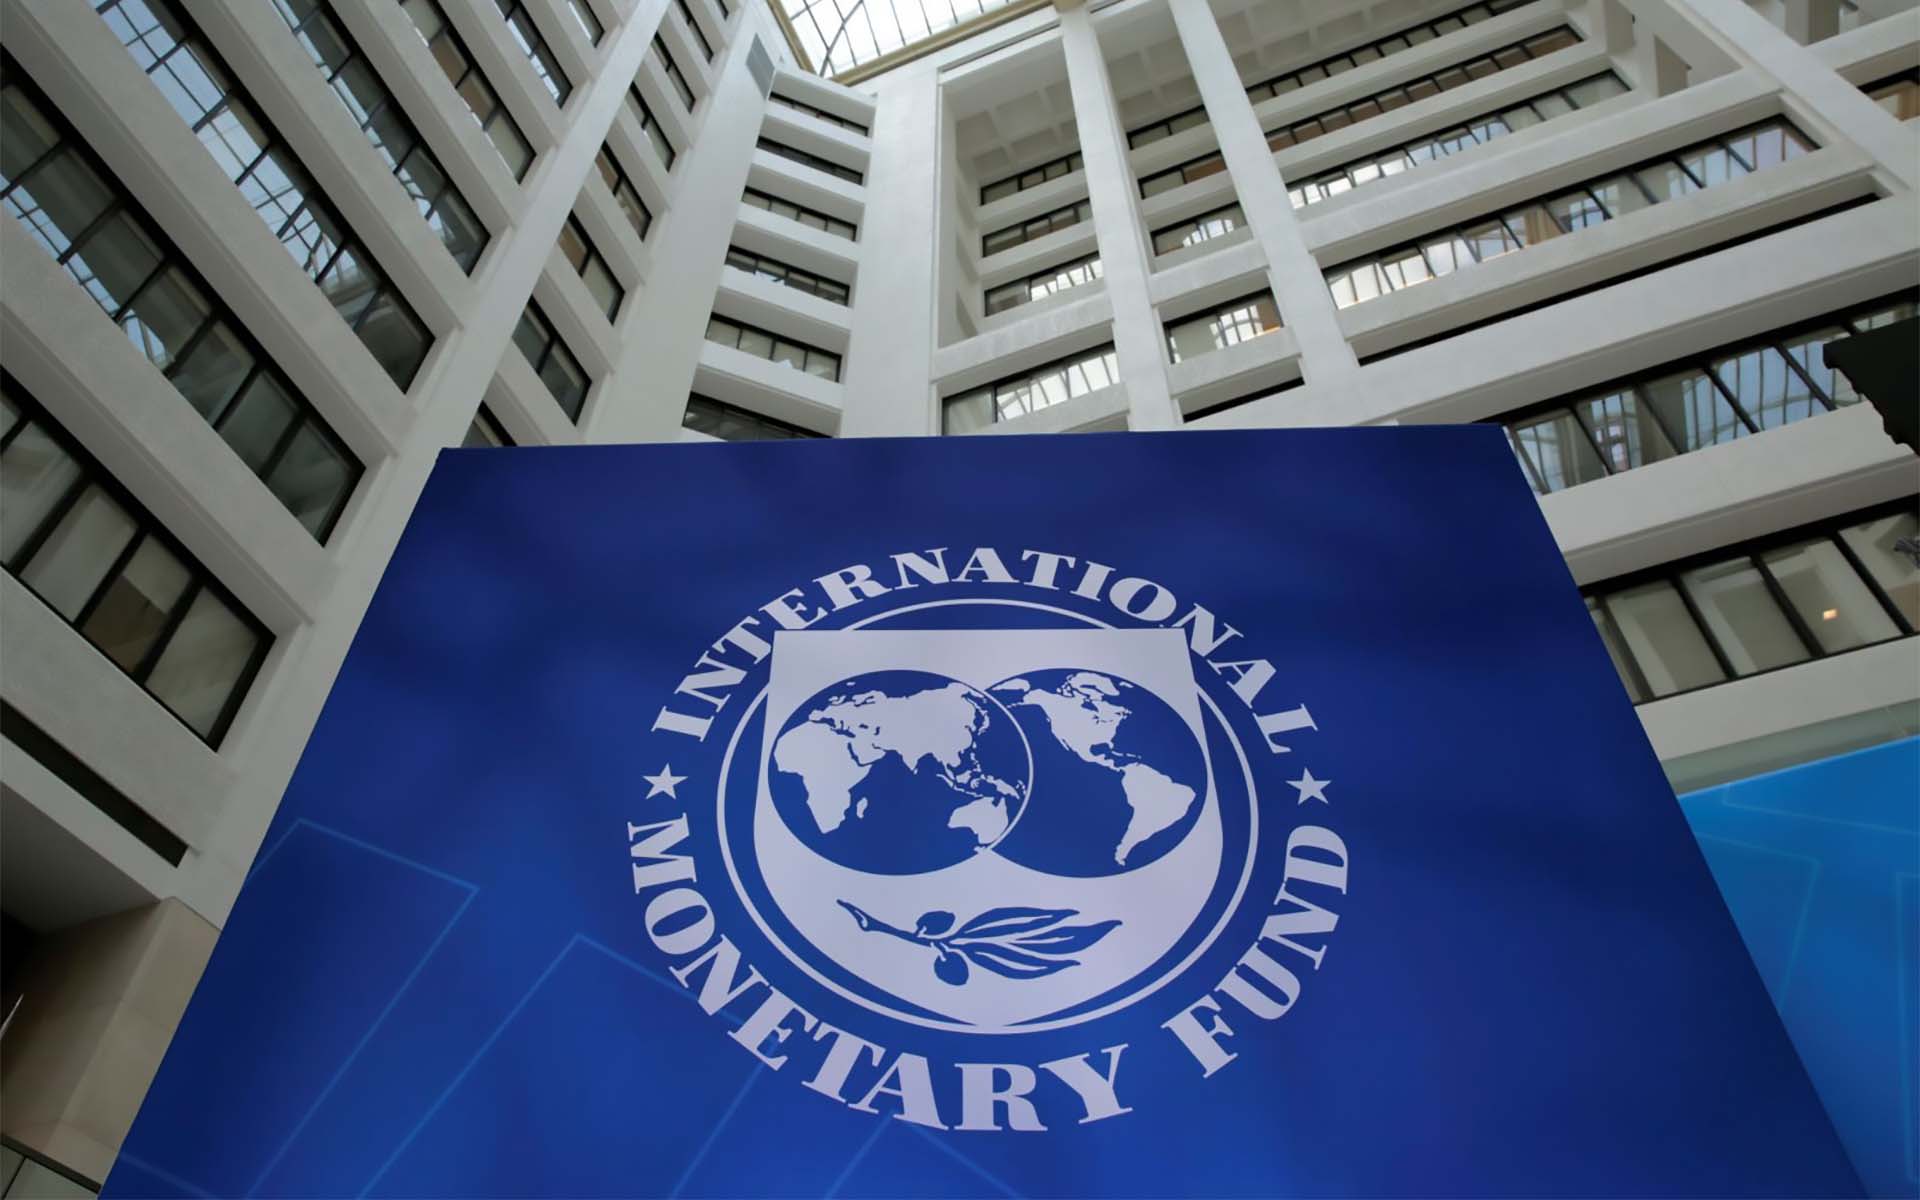
The International Monetary Fund (IMF) has identified four critical priorities for Nigeria as the country seeks to harness the growing use of dollar-pegged stablecoins for cross-border payments while safeguarding monetary stability and financial integrity.

In a new Country Focus note released as part of Nigeria’s 2026 Article IV consultation, the IMF said stablecoins have emerged as a practical solution to longstanding inefficiencies in remittance and international payment systems, offering faster and cheaper transactions than traditional channels.

The report was authored by IMF Mission Chief for Nigeria, Axel Schimmelpfennig, and Bo Zhao.

The Fund noted that stablecoins have gained significant traction in Nigeria, driven by the need for affordable cross-border transfers, access to dollar-denominated assets, and protection against currency volatility. However, it warned that their rapid adoption also presents risks, including digital dollarisation and challenges in monitoring illicit financial flows.

To address these concerns, the IMF urged Nigerian authorities to sustain macroeconomic reforms aimed at strengthening confidence in the naira and preserving monetary stability. According to the report, maintaining a credible domestic currency remains the most effective defence against excessive reliance on foreign-currency-backed digital assets.

The Fund also called for stronger regulatory oversight, recommending that Nigeria establish clear rules for stablecoin issuers and align its regulatory framework with emerging international standards while adapting them to local realities.

In addition, the IMF stressed the need for improved data collection and monitoring through the integration of blockchain analytics and reporting mechanisms covering naira-to-stablecoin transactions. Such measures, it said, would enable regulators to identify emerging risks and respond more effectively.

See also  NEPC, trade centre partner stakeholders on sesame, cowpea export compliance

The fourth recommendation focuses on upgrading payment infrastructure to support faster, cheaper and more interoperable cross-border transactions, thereby reducing dependence on informal and less-regulated payment channels.

Nigeria has become one of the world’s leading markets for crypto assets and stablecoins. According to the IMF, the country received about $59 billion in crypto-asset inflows between July 2023 and June 2024. Nigeria ranked second globally in the 2024 Chainalysis Global Crypto Adoption Index and sixth in the 2025 edition, accounting for roughly 60 per cent of sub-Saharan Africa’s stablecoin inflows since 2019.

The report attributed the growth to several factors, including smartphone-based instant settlements, lower transaction costs, high inflation, naira depreciation and foreign exchange restrictions experienced between 2023 and 2024. Stablecoins are increasingly being used for remittances, international supplier payments and as a store of value against local currency fluctuations.

The IMF acknowledged that wider stablecoin adoption could enhance financial inclusion, support trade and improve remittance flows. Nevertheless, it cautioned that extensive use of U.S. dollar-denominated stablecoins could weaken demand for the naira and reduce the effectiveness of domestic monetary policy.

It also highlighted concerns over financial integrity, noting that the migration of funds from regulated banking channels to digital wallets and exchanges could create gaps in anti-money laundering and counter-terrorism financing oversight.

The Fund concluded that stablecoins are likely to remain a permanent feature of the financial landscape, serving as a complement rather than a replacement for traditional financial systems. It urged Nigerian policymakers to balance innovation with effective regulation, arguing that the country’s long-term success will depend on maintaining confidence in the naira while building a robust supervisory framework capable of managing emerging digital financial risks.

See also  Personal loans hit new high N1.99tn

tribuneonlineng.com

FOLLOW US ON:

FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Business

Tinubu launches N52,500 minimum pension for 173,209 retirees

Published

on

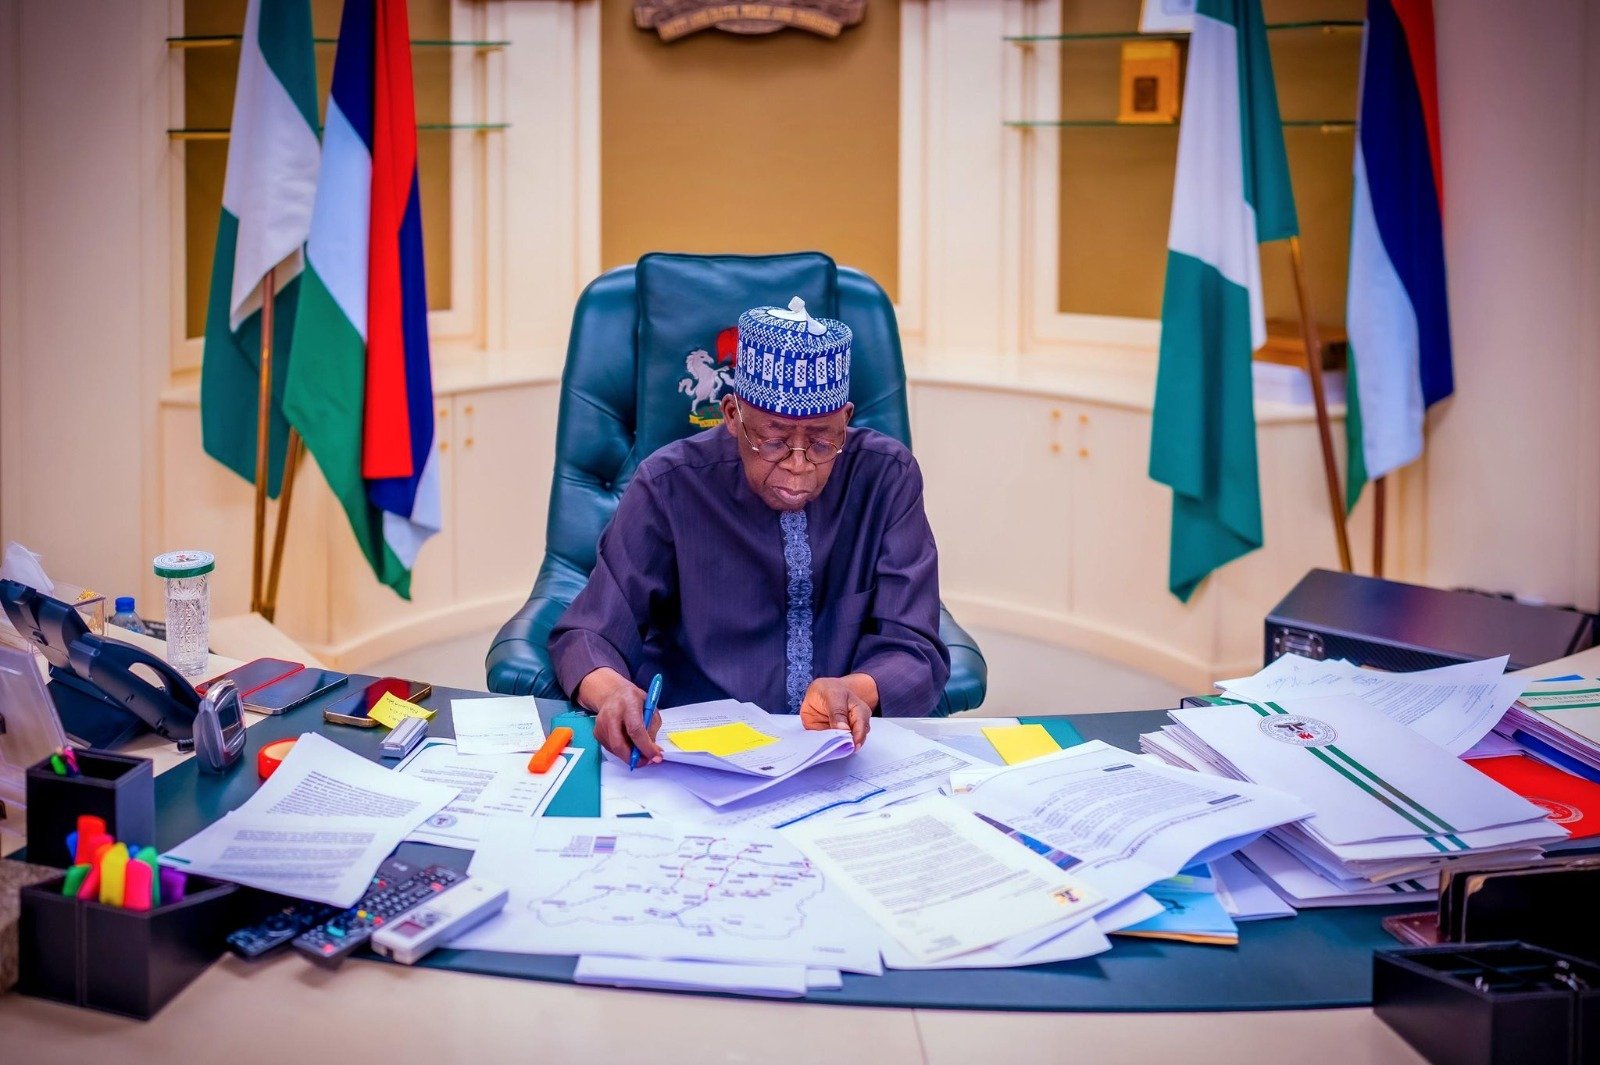
President Bola Tinubu on Tuesday launched a N52,500 monthly minimum pension guarantee for 173,209 eligible retirees under the Contributory Pension Scheme, ending a 22-year delay in implementing the provision of the Pension Reform Act.

The President also inaugurated the Pension Industry Healthcare Plan for Retirees, known as PenCare, to provide free essential healthcare services to low-income pensioners.

Tinubu, who was represented by Senate President Godswill Akpabio, announced the initiatives during the Presidential Pension Security Initiatives ceremony at the State House Banquet Hall, Abuja.

Declaring the minimum pension guarantee operational, he said, “By the authority vested in me as President, Commander-in-Chief of the Armed Forces of the Federal Republic of Nigeria, I hereby declare the Minimum Pension Guarantee Scheme commenced.”

The President explained that the guarantee, first provided for under the Pension Reform Act of 2004 and retained in the 2014 legislation, had remained unimplemented despite successive administrations.

“From this day, there is a floor beneath the Nigerian retiree. No one who contributed under the Contributory Pension Scheme will ever be allowed to fall below,” he said.

Tinubu urged future administrations to maintain the guarantee, declaring, “Raise it. But never remove the floor.”

On healthcare, he said the PenCare initiative would protect vulnerable retirees from medical expenses capable of exhausting their pension savings.

“PenCare gives our low-income retirees access to essential health care without charge,” he said, adding that beneficiaries would begin receiving healthcare access cards in the coming months.

The President also disclosed that his administration had issued a N758bn bond to address longstanding pension arrears and approved a N32,000 monthly consequential adjustment for affected federal pensioners.

He said states had spent over N1tn settling pension obligations, attributing their improved financial capacity partly to subsidy removal.

See also  NEPC, trade centre partner stakeholders on sesame, cowpea export compliance

Citing a World Bank report, Tinubu said states’ revenues increased by about 93 per cent in real terms between 2023 and 2025, while the share of their budgets devoted to capital projects rose from 46 to 61 per cent.

He also disclosed that government-backed credit initiatives had unlocked over N64bn for 174,000 borrowers, while more than 350,000 Nigerians had accessed approximately N53bn in consumer credit.

In her opening remarks, the Director-General of the National Pension Commission, Omolola Oloworaran, announced that the guaranteed minimum pension had been fixed at N52,500 monthly.

“The minimum pensions in the Federal Republic of Nigeria is 52,500 naira every month,” she said.

According to her, 173,209 retirees qualify for the guarantee, comprising 34 per cent from federal service, 12 per cent from state employment and 54 per cent from the private sector.

She explained that the amount had been actuarially validated and would be subject to periodic review.

“The figure was not plucked from the air. It has been validated by an actuary, and it is subject to review,” Oloworaran noted.

She disclosed that more than N400bn was available in the Pension Protection Fund to finance the guarantee, while more than 65 per cent of private-sector retirees currently earned below the new threshold.

The PenCom boss also revealed that states inherited over N2tn in pension liabilities, of which N1.07tn had been settled.

Source: punchng.com

FOLLOW US ON:

FACEBOOK

WHATSAPP CHANNEL

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

NERC okays N30bn to meter Band A customers, read details

Published

on

The Nigerian Electricity Regulatory Commission (NERC) has approved N30bn for the third phase of the Meter Acquisition Fund to accelerate the installation of electricity meters for unmetered Band A customers and expand coverage among Band B consumers.

The regulator has also directed electricity distribution companies to complete all meter installations under the programme by 31 May, 2027, warning that customers must not be charged for meters provided through the initiative.

The commission disclosed this in Order No. NERC/2026/121 on the operationalisation of Tranche C of the Meter Acquisition Fund, effective 2 November, 2026. It announced the order in a post on its official X handle on Tuesday.

The post read, “The Nigerian Electricity Regulatory Commission (NERC or the Commission) hereby informs electricity consumers and stakeholders of the issuance of Order No. NERC/2026/121 on the Operationalisation of Tranche C of the Meter Acquisition Fund, effective 2 November 2026.

“The Commission has approved N30 billion for Tranche C, to be allocated among the eleven Distribution Companies (DisCos) in proportion to their respective contributions to the Fund. The funding is intended to meter all remaining unmetered Band A customers and accelerate the metering of Band B customers, with equitable distribution across states within the respective DisCo franchise areas.”

The latest funding is part of the Federal Government’s Presidential Metering Initiative, which seeks to close the country’s persistent electricity metering gap, protect consumers from estimated billing and improve accountability in the power distribution system.

According to the order, the approved N30bn will be shared among the 11 electricity distribution companies in proportion to their respective contributions to the Meter Acquisition Fund.

See also  NEPC, trade centre partner stakeholders on sesame, cowpea export compliance

The funds will be used to provide meters for all remaining unmetered Band A customers while accelerating installations for Band B consumers. The commission also directed that the distribution should be equitable across states within each DisCo’s franchise area.

Under the arrangement, the distribution companies are required to conduct transparent procurement exercises involving eligible Local Meter Manufacturers and Assemblers and Meter Asset Providers with verified meter stocks.

NERC said it had prescribed maximum procurement prices based on the median national bid prices submitted by Meter Asset Providers during the September 2026 bidding cycle.

The commission also introduced a two-stage payment arrangement to strengthen accountability and ensure that providers deliver the meters before receiving full payment.

Under the arrangement, 70 per cent of the contract payment will be released after verification of delivered meter stocks, while the remaining 30 per cent will be paid after the complete installation of the meters has been confirmed.

The regulator reiterated that all meters supplied and installed under the fund must be provided free of charge to electricity consumers, warning against attempts by distribution companies or their agents to sell them.

It further directed that every meter supplied under the programme must prominently display the name of the relevant distribution company, the applicable tranche of the Meter Acquisition Fund and the inscription, “NOT FOR SALE”.

“The Commission reiterates that all meters supplied and installed under the MAF programme shall be provided FREE OF CHARGE to customers. Every meter must prominently display the relevant DisCo’s name, the applicable MAF tranche and the inscription “NOT FOR SALE.

See also  Revenue boom: World Bank faults states’ spending priorities, read full details

“Where a DisCo initiates the relocation of an existing customer’s connection point for revenue protection purposes, the cost shall be borne by the DisCo. The Order also provides sanctions where DisCo defaults impede meter installation,” the report added.

The order also addressed situations where distribution companies relocate customers’ existing connection points for revenue protection purposes.

According to NERC, where a DisCo initiates such relocation, it must bear the associated cost rather than transfer the financial burden to the affected customer.

The commission also provided for sanctions where defaults by distribution companies obstruct or delay meter installations, reinforcing the responsibility of operators to ensure that the programme is implemented within the stipulated period.

To prevent diversion of funds and ensure proper implementation, the regulator prescribed monitoring, reporting and evaluation requirements for the Fund Manager, distribution companies and participating meter providers.

It also directed that all supply and installation contracts executed under Tranche C must be submitted to the commission.

Source: punchng.com

FOLLOW US ON:
FACEBOOK

WHATSAPP CHANNEL

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

NDIC laments debtors’ refusal to repay failed bank loans

Published

on

The Nigeria Deposit Insurance Corporation has expressed concern over the refusal of some debtors of failed banks to repay outstanding loans, accusing them of deliberately frustrating recovery efforts through asset concealment, legal delays and intimidation.

The corporation warned that such practices undermine efforts to recover funds belonging to depositors and delay the payment of outstanding claims to customers of liquidated financial institutions.

The Director of the Asset Management Department of the NDIC, Ogungbemi Theophilus, raised the concerns on Monday during the Stakeholders’ Seminar and Public Relations Workshop held at Exclusive Serene Hotels and Suites, Wuye, Abuja.

Speaking on the challenges confronting the corporation in recovering assets of failed banks, Theophilus said, “Some debtors of failed banks believe that because a bank’s licence is revoked, he is not obliged to fulfil his responsibilities anymore. They hide assets. They frustrate service. Employ delay tactics in court. Sometimes, they try to intimidate. But we have to always do our job and professionally too.”

He explained that recovering outstanding loans remained one of the most difficult aspects of bank liquidation, particularly when borrowers failed to honour their obligations before the affected institutions lost their operating licences.

“A loan that was not repaid when the bank was alive does not become easier to recover when the bank is dead,” he noted.

The director noted that delays in recovering loans and disposing of physical assets could significantly reduce their value, ultimately affecting the amount available for distribution to depositors.

According to him, buildings left unoccupied for extended periods depreciate, while equipment deteriorates and outstanding loans become increasingly difficult to recover.

See also  143 firms battle for 50 oil blocks today; read details

“Every delay slows payment to depositors,” he warned.

Theophilus explained that the Asset Management Department was responsible for managing the loans, physical assets and investments of closed deposit money banks, primary mortgage banks and microfinance banks.

He said the department was mandated to recover outstanding loans, dispose of properties and investments, and convert recovered assets into cash to settle uninsured depositors.

He stressed that the corporation’s ability to compensate depositors whose balances exceeded the insured limits depended largely on the success of these recovery efforts.

The director explained that depositors of deposit money banks, non-interest banks and mobile money operators were insured up to N5m per depositor per bank, while those of microfinance banks, primary mortgage banks and payment service banks were covered up to N2m.

He said the existing coverage fully protected approximately 99 per cent of depositors, but customers with balances above the insured limits depended on liquidation dividends for the recovery of their outstanding funds.

“For them, the insured payment is only the first instalment. The balance — the uninsured deposit — can only be paid as liquidation dividend, from the proceeds of the assets we are able to realise and the loans we are able to recover,” he explained.

Theophilus disclosed that the corporation conducted public auctions through competitive sealed bidding on November 3 and 4, 2026, to dispose of physical assets belonging to three banks in liquidation.

He identified the institutions as Union Homes Savings and Loans, Heritage Bank, and Resort Savings and Loans, adding that the auctions took place in Lagos, Taraba and Adamawa states.

See also  World Bank flags ‘hidden spending system’ diverting over N34.53tn of Nigeria’s revenue

He said the exercises were coordinated by the Asset Management Department and executed by appointed auctioneers.

The director also cautioned against excessive recovery costs, stressing that expenses incurred in recovering debts must not outweigh the value of recovered assets.

“If it costs us N10m to recover N8m, the depositor has lost. We must be disciplined about costs, timelines and reporting,” he said.

He further warned professionals engaged in asset recovery against insider dealing, deliberate undervaluation, collusion with buyers and diversion of proceeds.

“The Corporation has zero tolerance for insider dealing, under-valuation, collusion with buyers, diversion of proceeds, or any conduct that short-changes depositors,” he declared.

Theophilus announced that the NDIC was developing a comprehensive Asset Management Policy to strengthen asset identification, documentation, valuation, disposal procedures and accountability in recoveries.

He said the corporation would also deepen collaboration with auctioneers, valuers, sales agents, surveyors and other professionals to improve loan recoveries and accelerate the settlement of depositors’ claims.

The director explained that the Abuja workshop formed part of three stakeholder seminars scheduled for Abuja, Enugu and Lagos, aimed at identifying operational challenges, strengthening professional relationships and improving asset recovery outcomes.

He maintained that successful collaboration would ultimately benefit depositors awaiting payment following the collapse of their banks.

Source: punchng.com

FOLLOW US ON:

FACEBOOK

WHATSAPP CHANNEL

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Trending