Connect with us

Business

FG’s N9tn domestic loans surge drains lifeline from businesses

Published

on

The Federal Government’s domestic borrowings from financial market operators rose sharply in 2025 despite high interest rates, widening the gap between public and private sector access to credit, according to data obtained from the Central Bank of Nigeria on Thursday.

An analysis of money and credit statistics showed that credit to the Federal Government outpaced private sector borrowings by N9.19tn, representing a 695.6 per cent swing in 2025, reflecting heightened fiscal pressures and increased reliance on local funding sources.

In contrast, net credit to the private sector declined by N1.543tn in 2025, highlighting the challenges faced by businesses amid tight monetary conditions and elevated interest rates. This divergence underscored a growing imbalance in the allocation of financial system resources, with the public sector absorbing a larger share of available liquidity.

The trend points to a classic crowding-out effect, as rising government demand for funds limits banks’ capacity to extend credit to the productive sector, while many organised businesses increasingly prioritise settling existing debts rather than taking on new borrowing.

The PUNCH reports that in monetary and financial statistics, credit to government refers to funds extended to the Federal Government by the domestic financial system, mainly through the purchase of government securities such as Treasury bills, bonds, and other debt instruments, as well as direct lending by banks and other financial institutions.

This form of credit is typically used to finance budget deficits, refinance maturing obligations, support capital and recurrent expenditure, and manage short-term cash flow gaps when government revenues fall short of spending needs.

Credit to the private sector, on the other hand, represents loans and advances granted by banks and other financial institutions to businesses, households, and non-government entities. It is primarily used to fund working capital, business expansion, investment in plant and machinery, trade, agriculture, services, and consumer spending. Growth in private sector credit is widely regarded as a key indicator of economic activity, as it supports production, job creation, and overall economic growth.

In practice, when government borrowing from the financial system rises sharply, especially in a high-interest-rate environment, it can reduce the pool of funds available for private sector lending, a phenomenon often described as crowding out. This dynamic can raise borrowing costs for businesses and slow investment, even as the government secures financing to meet its fiscal obligations.

An analysis of CBN money and credit statistics obtained showed that credit to the Federal Government rose by N9.192tn in 2025, while credit to the private sector declined by N1.543tn over the same period.

The data highlight intensifying concerns over crowding-out effects, as the government’s rising appetite for domestic funds coincided with shrinking credit to businesses and households.

According to the CBN data, credit to the public sector increased significantly in 2025, rising from N25.03tn in January to N34.22tn by December, translating to a N9.19tn increase within the year. It also represented an increase of N5.57tn, or nearly 154 per cent, compared with the N3.62tn government credit recorded in 2024.

A month-on-month breakdown revealed that government credit stood at N25.03tn in January 2025 before rising by N2.08tn, or 8.3 per cent, to N27.11tn in February. This was followed by a contraction of N2.52tn (9.3 per cent) in March to N24.59tn, and a further dip of N655bn (2.7 per cent) in April to N23.93tn. Borrowing eased again in May, falling by N946bn (4.0 per cent) to N22.99tn, and declined by another N1.33tn (5.8 per cent) in June to N21.66tn, marking the lowest level for the year.

Government credit rebounded in July, increasing by N2.03tn (9.4 per cent) to N23.69tn, before slipping by N740bn (3.1 per cent) to N22.95tn in August. The upward trend resumed in September, with credit rising by N1.21tn (5.3 per cent) to N24.16tn, followed by a N629bn (2.6 per cent) increase in October to N24.79tn. In November, borrowing grew further by N1.57tn (6.3 per cent) to N26.35tn, before surging sharply in December by N7.87tn, or 29.9 per cent, to close the year at N34.22tn.

In contrast, net credit to the private sector contracted by N1.54tn in 2025, reflecting tight liquidity conditions and elevated borrowing costs. Private sector credit declined from N77.38tn in January to N76.26tn in February, representing a N1.12tn or 1.4 per cent drop. This was followed by a marginal decline of N276bn (0.4 per cent) in March to N75.98tn.

See also  FG warns 3,598 workers of dismissal, orders fresh verification

Borrowing rebounded in April, rising by N2.09tn (2.7 per cent) to N78.07tn, before easing slightly by N100bn (0.1 per cent) to N77.97tn in May. Credit fell sharply in June by N1.84tn (2.4 per cent) to N76.13tn, but edged up in July by N598bn (0.8 per cent) to N76.72tn. August recorded another contraction of N841bn (1.1 per cent) to N75.88tn, followed by a steep decline of N3.36tn (4.4 per cent) in September to N72.53tn, the lowest point for the year.

Private sector credit recovered modestly in October, increasing by N1.88tn (2.6 per cent) to N74.41tn, and edged up by N220bn (0.3 per cent) in November to N74.63tn. In December, borrowing rose by N1.20tn (1.6 per cent) to close the year at N75.83tn, still well below the January level.

For context, government borrowing from the financial system increased by N3.62tn in 2024, far lower than the N9.19tn expansion recorded in 2025, while private sector credit grew by N1.54tn in 2024 but reversed into a contraction of N1.543tn in 2025.

A comparison of borrowing from the domestic financial system showed that government credit accelerated sharply in 2025 compared with 2024, beginning from January, when credit to the Federal Government rose to N25.03tn in 2025, up from N23.52tn recorded in January 2024.

In January, government credit stood at N25.03tn in 2025, up N1.51tn or 6.4 per cent from N23.52tn recorded in January 2024. By February, credit rose to N27.11tn, representing a sharp N8.69tn or 47.2 per cent increase compared with N18.43tn in February 2024.

However, in March, government borrowing moderated to N24.59tn, still N4.54tn or 22.6 per cent higher than N20.05tn in March 2024. In April, credit stood at N23.93tn, an increase of N3.96tn or 19.8 per cent over N19.98tn in April 2024.

In May, CPS declined year-on-year, falling to N22.99tn in 2025, which was N5.39tn or 19.0 per cent lower than the N28.38tn recorded in May 2024. The downward trend continued in June, with credit at N21.66tn, down N2.27tn or 9.5 per cent from N23.93tn in June 2024.

Government borrowing also trailed 2024 levels in July, standing at N23.69tn, which was N3.87tn or 19.5 per cent higher than July 2024’s N19.83tn, reflecting a rebound. In August, credit dropped sharply year-on-year to N22.95tn, a decline of N8.20tn or 26.3 per cent from N31.15tn in August 2024.

In September, CPS stood at N24.16tn, representing a steep N15.31tn or 38.8 per cent drop compared with N39.47tn recorded in September 2024. October followed a similar pattern, with government credit at N24.79tn, down N14.60tn or 37.1 per cent from N39.39tn in October 2024.

In November, credit rose to N26.35tn, but was still N13.26tn or 33.5 per cent lower than N39.62tn recorded a year earlier. By December, however, borrowing surged to N34.22tn, exceeding N27.14tn in December 2024 by N7.08tn or 26.1 per cent, driving the overall annual increase of N9.19tn in 2025.

Private sector borrowing showed a contrasting pattern. In January 2025, credit stood at N77.38tn, up N898bn or 1.2 per cent from N76.48tn in January 2024. However, in February, borrowing dropped to N76.26tn, a sharp N4.97tn or 6.1 per cent decline compared with N81.22tn recorded in February 2024.

In March, private sector credit stood at N75.98tn, N4.55tn or 6.4 per cent higher than N71.43tn in March 2024. April also recorded an increase, with credit rising to N78.07tn, up N5.15tn or 7.1 per cent from N72.92tn a year earlier.

By May, borrowing rose to N77.97tn, an increase of N3.66tn or 4.9 per cent over N74.31tn in May 2024. In June, credit stood at N76.13tn, up N2.94tn or 4.0 per cent compared with N73.19tn in June 2024.

The trend reversed in July, as credit eased to N76.72tn, marginally N1.22tn or 1.6 per cent higher than N75.51tn in July 2024. In August, borrowing declined to N75.88tn, N1.15tn or 1.5 per cent higher than N74.73tn in August 2024, indicating stagnation.

In September, private sector credit fell sharply to N72.53tn, down N3.31tn or 4.4 per cent from N75.83tn in September 2024. October followed with N74.41tn, a slight N339bn or 0.5 per cent increase over N74.07tn in October 2024.

See also  Price Of Bag Of Dangote, BUA, Other Cement This Week

In November, borrowing slipped to N74.63tn, N1.33tn or 1.8 per cent lower than N75.96tn in November 2024. By December, credit stood at N75.83tn, representing a N2.19tn or 2.8 per cent decline from N78.02tn recorded in December 2024, culminating in a N1.54tn net contraction for 2025.

Commenting on behalf of the Organised Private Sector and the manufacturing industry, the Director-General of the Manufacturers Association of Nigeria, Segun Kadir Ajayi, said credit data from the financial system point to a clear crowding-out of private sector borrowing by government demand.

In a telephone interview on Thursday, Ajayi said the trend reflects the preference of commercial banks and other financial institutions to lend to government, given prevailing interest rates and perceived lower risk, to the detriment of productive sectors of the economy.

The MAN DG said, “The data is a trend that proves something. Usually when you see such trends, it is indicative of the private sector being crowded out in terms of borrowing. Because when you borrow, you would repay and so the rate at which you borrow is critical for your operations and when commercial banks and financial institutions find it a lot easier to lend to government rather than to the private sector.”

Ajayi noted that the manufacturing sector has been particularly affected, with many firms scaling back borrowing for expansion and raw material sourcing amid high costs and weak economic conditions.

According to him, the slowdown in private sector credit is consistent with the broader lack of economic buoyancy, including weak consumer demand and limited liquidity in the system.

“You also have discovered that the manufacturing sector has been challenged and so borrowing for expansion and raw material sourcing has been low keyed.  So you would expect less credit because there has been no bouyancy in terms of purchases and in terms of the funds available. So you should expect this type of trend. Many manufacturers are simply not in a position to take on expensive credit,” he added.

He, however, said the development underscores the need for deliberate policy intervention to stimulate industrial growth through targeted financing.

“But what this means is that government should be intentional with about making low cost credit available to the sector, so that you can stimulate their appetite for borrowing and work to expand, scale and not working to pay the banks. This is just the simple explanation,” he advised.

Economist reacts

In his expert comment on the issue, Muda Yusuf, renowned economist and Chief Executive Officer of the Centre for the Promotion of Private Enterprise, warned that rising Federal Government borrowing from the domestic financial system is increasingly crowding out the private sector, as banks favour low-risk, high-yield government securities over lending to businesses.

Yusuf noted that while the private sector still accounts for a larger share of total outstanding credit in absolute terms, the direction of credit flow is a growing concern.

“The increase in credit to the government can be attributed to a number of factors. The government has been raising money to finance the deficit. So this financing of deficit has led to the issuance of bonds, treasury bills and so on, which banks also buy. The rate is also very attractive and it’s more attractive to them than to be lending to the real sector,” Yusuf said in a telephone conversation with our correspondent

According to him, the surge in government borrowing is largely driven by the need to finance widening fiscal deficits, which has translated into increased issuance of Treasury bills, bonds and other government securities. Yusuf noted that the prevailing interest rate environment has further tilted banks’ preference towards government instruments.

“The second point is that the risk of lending to government is extremely very low because it is a sovereign debt and government can’t come back to you and say they won’t pay back. It won’t happen. Except for those local contractors. But if it is through the financial system, they raise funds through government bonds. So the risk is low, rates are very attractive and the banks normally prefer this option because they are more comfortable,” he said.

See also  Comedian Broda Shaggy hospitalised after alleged shooting

He added that, unlike private sector lending, government borrowing through the financial system carries minimal default risk. “If it is through the financial system, funds are raised through government bonds. The risk is low, rates are attractive, and banks are more comfortable with that option,” Yusuf said. “Lending to the private sector is riskier for them.”

As a result, he said the private sector is increasingly unable to compete with the government for credit. “To that extent, you can say the government is gradually crowding out the private sector,” he stated. “They cannot compete with the government when it comes to credit. The risk for bonds is low, but the interest rate is high.”

Yusuf said this dynamic has intensified calls for the government to moderate its borrowing. On the private sector side, Yusuf pointed to persistently high interest rates as a major deterrent to borrowing and investment. He explained that while the government can raise funds by issuing bonds without negotiating loans with banks, private businesses face tougher conditions.

“There is a bit of crowding-out, and that’s why some people are arguing that government should borrow less, so that they don’t crowd out the private sector.

“The second point on the private sector side is that the interest rate is still high. So there is no business you can do with credit facilities of up to 30 per cent. The Monetary Policy Rate is still at 27 per cent. But for the government, they only have to issue bonds, they won’t have to meet banks for loans, only the state government meet government for loans and pays back through FAAC allocations. These are some of the issues,” he said.

Commenting on what declining private sector credit signals about the economy, Yusuf said it should be a major concern for policymakers.

“Of course, it indicates that something is not right in the economy. It should be a concern for the government, because with the interest rate at that level, how do you want to promote investment? It should be a concern. The private sector borrows to invest, so if it’s not there, it will affect growth. The government is only borrowing to finance the deficit.

“We want the banks to support the private sector more than they are doing now. You can also do some comparison with what other banking institutions are doing in other countries. You would observe that it is low compared to other countries. Our credit to the private sector compared to Gross Domestic Product shows the level of the financial system is supporting the sector,” he warned.

The economist also noted that Nigeria’s private sector credit levels remain weak compared to peer economies. On solutions, Yusuf said restoring balance in credit allocation would require a combination of lower interest rates, reduced government borrowing, and stronger revenue mobilisation.

He added that improved revenue generation would ease pressure on the financial system. “The only solution is to move the economy in a way that the interest rate is lower for borrowing. Recapitalisation can help to support big investment, but the interest rate has to come down. Inflation has to come down. The government should borrow less and focus on revenue, so the funds can go to the private sector,” Yusuf concluded.

The surge in government borrowing comes amid persistent fiscal pressures, including rising debt servicing costs, revenue shortfalls, and increased spending obligations following fuel subsidy reforms and exchange rate adjustments.

At the same time, the CBN’s tight monetary stance, anchored on elevated interest rates to rein in inflation, has raised the cost of borrowing across the economy, disproportionately affecting the private sector.

With inflationary pressures persisting and interest rates remaining high, stakeholders say a rebalancing of credit allocation will be critical to support growth, job creation, and industrial expansion.

As Nigeria navigates ongoing fiscal and monetary reforms, the widening gulf between public and private sector borrowing is expected to remain a key indicator of the health, or strain, within the financial system.

punch.ng

FOLLOW US ON:
FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

TUMBLR

INSTAGRAM

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Business

Alakija, Okoli urge women to create value, make impact

Published

on

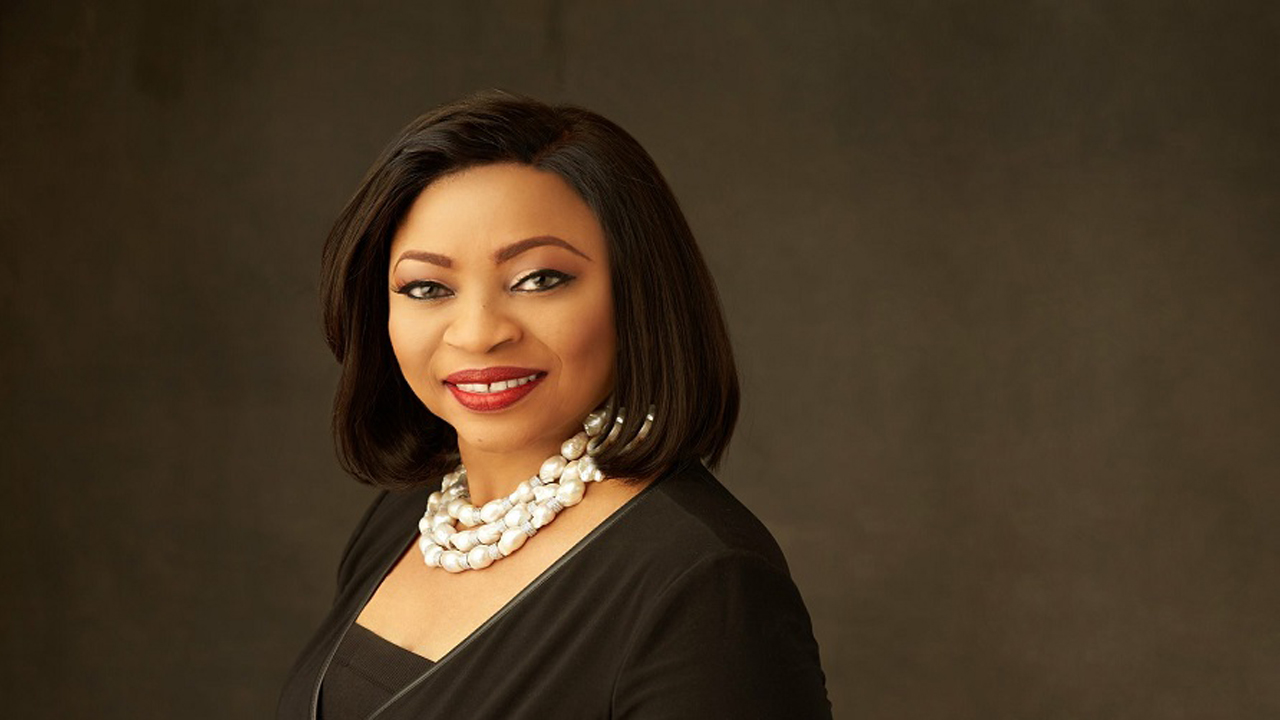
Businesswoman and philanthropist, Apostle Folorunso Alakija, has urged Nigerian women to move beyond having a voice to leading the transformation of society.

Alakija, who spoke as the keynote speaker at the 10th Voice of Women Conference and Awards in Lagos on Tuesday, said women must ensure that their voices translate into solutions and engender lasting change.

Alakija said, “A voice by itself is only potential. A voice may carry an idea; your voice may carry a solution; your voice may carry a business; your voice may carry wisdom that can change a young woman’s life. But if that voice remains inside you, the impact remains trapped.”

She argued that finding one’s voice was only the beginning, adding that women needed capacity to make meaningful use of opportunities.

“God can open a door, but we must develop the capacity to walk through it and be effective once we enter,” she said.

Alakija, who recalled her journey from office administration and banking into fashion, oil and gas, philanthropy and leadership, said women must progress from capacity to influence and ultimately to impact.

“Visibility is not the same as influence. You can be seen and still be insignificant. You can be popular and still not add value. You can have a title and still not be a leader. True influence comes when your presence makes a difference,” she said.

She urged women to use their success to address social problems, mentor younger women and provide solutions to communities, stressing that Nigeria needed women who would accept responsibility for the impact of their leadership.

“Nigeria doesn’t need successful women alone. It needs women who will use their success to solve problems,” Alakija said.

See also  Coalition demands Atiku and Obi’s full membership on 2027 Presidency

She added, “The question is no longer ‘What have we achieved?’ The question is, ‘What will remain because we were here?’”

Also speaking at the event, founder of Emzor Pharmaceutical Industries, Dr Stella Okoli, said women could use their voices to build businesses and industries that would contribute to national development.

Okoli, who spoke on “Voice to Value: Building Enterprise Industrial Enterprise that Empowers and Includes Nigeria,” said her life had been a journey “from vision to enterprise, from enterprise to value, from value to nation-building.”

She said, “If there is one message I want to leave with you today, it is that a voice becomes truly powerful when it creates value.”

According to her, a voice that builds a business, employs people, creates industries, solves national problems and leaves something for the next generation becomes “a force of transformation.”

Okoli, who founded Emzor in 1985 after starting a retail pharmacy business, recalled that she obtained a N6,000 loan from FirstBank to begin local production of Emzor Paracetamol.

She urged young women not to wait until they had everything before starting their businesses.

“You do not need to begin with everything, but you need to begin with something,” she said.

“Your first office may be a room, your first employee may be one person, and your first product may only be one product. But do not allow yourself to remain there.”

The pharmacist also urged the government to support local pharmaceutical manufacturers and young entrepreneurs, saying Nigeria should develop the capacity to produce the raw materials needed for medicines.

Earlier, founder of the Voice of Women Empowerment Foundation and Executive Director of Women Radio WFM 91.7, Toun Okewale-Sonaiya, in her welcome address, said the platform had moved from providing women with a space to speak to creating opportunities for their voices to produce tangible results.

Sonaiya said, “We have learned that voice is only the beginning, and real change happens when the voice becomes influence, when ideas become action, and when our action transforms lives.”

See also  FG, states target cheaper transport fares with CNG bus rollout

She said women now needed more than a platform, noting that they required “opportunity, real access, resources, representation, and the power to turn their own voice into impact.”

The founder said the conference had, over the past decade, evolved from discussions around economic empowerment, finance, agriculture and technology to issues including gender-based violence, governance and inclusion.

She also called for grassroots women living with disabilities to be represented in decision-making spaces.

“Women do not need to be spoken for. Women need to be heard and be empowered to shape solutions,” she said.

Sonaiya also used the occasion to draw attention to the story of Oluwatobi Raji, a survivor of trauma, rape, drug abuse, homelessness and teenage marriage who now educates more than 150 out-of-school children in Mowo, Ogun State.

She appealed for support to enable Raji to secure a permanent facility for the children.

“I am hoping that someone in this room has the resources, the connections, and the heart to say, ‘I will help Oluwatobi Raji build a permanent school for these children,’” she said.

Former First Lady of Ekiti State, Erelu Bisi Adeleye-Fayemi, urged women to raise daughters who would dream and aspire while raising sons who would respect women and understand responsibility.

Fayemi said women should not continue to participate in systems that undermine them, declaring, “Women have suffered enough. Girls are going through too much already. Women, we should stop investing in our own oppression.”

She also urged women to demand dignity, mutual respect, confidence and responsibility in relationships and to support other women rather than undermine them.

See also  Electricity reforms: Rivers, Kano, 19 others delay takeover

The Deputy Governor of Ogun State, Noimot Salako-Oyedele, called on women to support and mentor one another, saying their progress should create opportunities for others.

“As we rise, lift as you rise. It is very important so that as one goes, we do not go alone,” she said.

Salako-Oyedele, who recalled her relationship with Sonaiya since she became deputy governor in 2019, said Women Radio had created a platform for women to bring their experiences and aspirations into public conversations.

She said more still needed to be done in areas including economic opportunity, healthcare, education and women’s participation in governance.

Veteran broadcaster, Bimbo Oloyede, who recalled Sonaiya’s early efforts to establish a radio platform for women, urged the organisers to take the Voice of Women Conference beyond Nigeria.

Speaking, FirstBank Chief Executive Officer, Segun Alebiosu, represented by Helen Willie, said women’s voices needed to be backed by access to finance, business knowledge, technology, markets and networks.

He noted that women-owned businesses required support at different stages of growth, including assistance with record-keeping, cash flow, pricing, governance and access to larger markets.

“Voice is not enough. For women’s voices to create sustainable impact, they must be supported with access to finance, business knowledge, technology, markets, and strong networks,” he said.

Source: punchng.com

FOLLOW US ON:
FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

Consolidated Hallmark, CHI Life Assurance seek deeper broker partnerships

Published

on

Consolidated Hallmark Insurance Limited and CHI Life Assurance Limited have called for stronger collaboration among insurers, brokers and other industry stakeholders to accelerate the growth of Nigeria’s insurance sector.

The companies, both subsidiaries of Consolidated Hallmark Holdings Plc, made the call at the Ibadan Professional Brokers Forum, where they engaged insurance brokers on the need to build a more customer-focused industry.

The companies said closer cooperation across the insurance value chain would be critical to understanding customers’ changing needs, developing relevant products and rebuilding public confidence in insurance.

They emphasised the role of brokers as an important link between insurers and policyholders, particularly in identifying emerging risks and ensuring that insurance solutions are properly matched with customers’ need

Leading the charge were Managing Director/Chief Executive Officer of CHI Limited, Mrs. Mary Adeyanju, and Managing Director/Chief Executive Officer of CHI Life Assurance Limited, Mr. Tope Ilesanmi. Both called for deeper cooperation, bolder innovation and a sharper focus on the customer.

Speaking on business continuity, Adeyanju explained that insurance helps companies stay operational and recover after disaster strikes. “Business continuity is about ensuring that a company continues in business even after experiencing a catastrophe,” she said.

She placed brokers at the heart of the value chain due to their closeness to policyholders. “Brokers are the first respondents when a claim occurs. You are the first point of contact, and you know the reality of insurance,” she noted.

Adeyanju urged brokers to partner with underwriters to spot market gaps and shape products that solve real problems. “We need to develop products that speak to the needs of people, not just products created to sell insurance,” she said.

She also challenged the industry to reshape its image. “The insurance industry needs to get out of its shell. Underwriters and brokers must work together towards changing the history and narrative of the insurance industry,” she said. Brokers, she added, should help policyholders understand their coverage, their responsibilities and the true value of insurance.

See also  Tenure countdown: States owe N5.3tn as 12 govs near exit

On financial strength, she reassured participants that CHI Limited stands on solid ground after recapitalisation, with N52bn in capital and a readiness to work flexibly with brokers.

Ilesanmi traced CHI Life’s evolution from a micro life insurance company into a full life assurance business. He noted that its capital rose from N10bn to N11.2bn after recapitalisation, and that the company paid out about N1bn in claims over the past six months. “This reflects our commitment to meeting our obligations to our customers,” he said.

He pointed to Rent Secure as proof that gap driven innovation works. “We need to look for the gaps in the market and build products around those gaps. Rent Secure is an example of a product created to meet a specific need,” he explained.

His closing thought captured the spirit of the forum: “The future of insurance will not be built by insurance alone. It will be built through stronger partnerships between insurers and the insured, better products, stronger service, deeper customer understanding and, above all, trust.”

Both leaders highlighted the wider capabilities of the Consolidated Hallmark Holdings Plc Group, whose companies also offer financial services and health insurance solutions.

The forum underscored a shared conviction: stronger collaboration between brokers and underwriters improves customer experience and drives growth across Nigeria’s insurance industry. CHI and CHI Life reaffirmed their commitment to working with brokers and other stakeholders to raise service standards, deliver customer focused solutions and deepen trust in insurance.

Source: punchng.com

FOLLOW US ON:

FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

World Bank raises Nigeria growth forecast

Published

on

The World Bank has raised its 2026 growth forecast for Nigeria to 4.3 per cent, citing improving macroeconomic stability, recovering investor confidence and a gradual revival in private investment, but warned that rising government spending ahead of the 2027 elections could weaken the momentum of recent economic reforms.

The projection was contained in the bank’s October 2026 Africa Economic Update, titled Building AI Readiness, released on Tuesday. The report also raised Nigeria’s growth forecast for 2027 and 2028 to 4.4 per cent annually, compared with an estimated 4.0 per cent expansion in 2025.

“Economic activity in Nigeria is projected to strengthen from 4.0 percent in 2025 to 4.3 percent in 2026, before edging up to 4.4 percent annually in 2027–28,” the bank said.

The global lender attributed the expected improvement to greater macroeconomic stability, strengthening investor confidence and a gradual recovery in private investment.

The upgraded forecast follows stronger-than-expected economic performance in the second quarter of 2026, when Nigeria’s real Gross Domestic Product expanded by 4.43 per cent year-on-year, compared with 4.23 per cent in the corresponding period of 2025.

Agriculture expanded by 4.39 per cent, up from 2.82 per cent a year earlier, while services grew by 4.6 per cent. Real oil GDP rose by 7.3 per cent, although the sector contributed only 0.2 percentage points to overall growth.

Industrial growth, however, slowed sharply to 4.0 per cent from 7.5 per cent in the second quarter of 2025, highlighting uneven growth across sectors.

The World Bank identified financial services, information and communications technology and real estate as major growth drivers, supported by digitalisation and resilient domestic demand. Agricultural activity is also expected to recover in 2026, although the bank projected weaker momentum in the industrial sector because of softer growth in oil production and manufacturing.

Despite the improved outlook, the World Bank warned that rising government spending ahead of Nigeria’s 2027 general elections could undermine efforts to stabilise the economy and weaken the momentum of reforms.

See also  Airlines plan Thursday shut down; see why

Highlighting risks to Nigeria’s outlook, the Washington-based institution said, “Nevertheless, the outlook remains subject to significant downside risks, including tighter global financial conditions, a prolonged conflict in the Middle East, insecurity, climate-related shocks, disruptions to oil production, and rising pre-election spending ahead of the 2027 elections.”

It added, “These factors could weaken reform momentum and erode the social consensus needed to sustain ongoing macroeconomic adjustment efforts.”

The warning comes as Nigeria approaches the 2027 election cycle following a series of major economic reforms implemented by the Federal Government since 2023, including the removal of petrol subsidies, foreign exchange market reforms and efforts to raise government revenue.

The World Bank noted that sustaining politically difficult reforms could become harder as elections approach, particularly when households are still struggling with high living costs.

It said several governments across sub-Saharan Africa had recently undertaken difficult measures, including “fuel subsidy removal, exchange rate liberalisation, fiscal consolidation, and efforts to strengthen domestic revenue mobilization.”

According to the bank, reform momentum could become harder to sustain ahead of elections or during periods of intense political competition. It warned that the danger went beyond a temporary slowdown in reforms, noting that public backing could weaken if painful measures failed to produce visible improvements in living standards within a reasonable period.

The bank said this could reduce the willingness of both governments and citizens to support similar reforms in the future and potentially increase pressure for populist economic policies.

The World Bank also expects Nigeria’s inflation rate to maintain a downward trajectory following monetary tightening, exchange-rate stabilisation and improving supply conditions.

It projected inflation to fall from 23.0 per cent in 2025 to 15.7 per cent in 2026 and further to 12.2 per cent by 2028. “Lower inflation is expected to support household purchasing power and contribute to a gradual reduction in poverty,” the report said.

However, the bank cautioned that faster economic growth alone may not be enough to significantly improve living standards, as the pace at which poverty is declining remains weak because growth in income per person continues to trail overall economic expansion.

See also  26 states lean on FAAC as wage bills outstrip IGR

It said poverty reduction could remain constrained by elevated fuel prices associated with the conflict in the Middle East, which have placed a bigger burden on low-income households.

This means that even as headline economic indicators improve, households continue to feel pressure from high living costs, particularly where wage growth and employment opportunities fail to keep pace with inflation and other expenses.

The bank also warned governments against fiscal slippages as political pressures increase, saying elevated debt-service obligations continued to restrict fiscal space while inflation remained vulnerable to exchange-rate depreciation, food-price shocks and loose fiscal policy.

It stressed that preserving central bank independence and avoiding monetary financing of government deficits would remain critical to keeping inflation expectations anchored as African economies navigate approaching election cycles and renewed global economic uncertainty.

The Governor of the Central Bank of Nigeria, Olayemi Cardoso, earlier said the CBN was prepared to contain excess liquidity as Nigeria approaches another election cycle.

“We are ready,” he said during a press briefing at the end of the 307th meeting of the CBN’s Monetary Policy Committee in Abuja, explaining that the bank had analysed previous election cycles and developed different scenarios.

He said the CBN would monitor currency in circulation, banking system liquidity, monetary aggregates and foreign exchange demand. “We will proactively deploy any tools and instruments to mop up any excess liquidity,” Cardoso said. “We will not allow ourselves to be caught unaware in any form.”

Meanwhile, the World Bank said Nigeria was among the African economies whose growth outlook had been revised upwards, reflecting the effects of economic reforms and improvements in macroeconomic management.

See also  Tinubu picks Disu for pre-2027 security boost, DIGs to retire

More broadly, the World Bank raised its growth projection for sub-Saharan Africa to 4.3 per cent in 2026, up from 4.1 per cent in 2025 and 0.3 percentage points higher than its April projection.

Nigeria was among nearly three-quarters of countries in the region whose 2026 growth forecasts were upgraded. World Bank Chief Economist for Africa, Andrew Dabalen, said the region had demonstrated resilience despite a challenging global environment, including higher energy prices linked to disruptions arising from the Iran conflict.

However, the bank cautioned that the region must do more to convert economic expansion into broad-based improvements in living standards.

The World Bank said sustained reforms, increased private investment, improved infrastructure, stronger human capital and higher productivity would be critical to turning macroeconomic stability into meaningful gains for households.

It also urged African economies to accelerate the adoption of artificial intelligence and other digital technologies as a way of raising productivity and creating new employment opportunities.

It said the continent would need to exploit emerging technologies while simultaneously addressing persistent gaps in infrastructure, skills and access to digital services.

The bank projected Nigeria’s current-account surplus to widen from 4.8 per cent of GDP in 2025 to 6.0 per cent in 2026 before narrowing to 3.4 per cent by 2028 as crude prices normalise and import demand recovers.

It also noted that Nigeria, as an oil exporter, was less directly exposed to the global energy shock than many African economies, although its capacity to withstand wider economic effects would depend on the strength of its policy buffers and institutions.

Higher crude oil prices could provide some relief by strengthening Nigeria’s fiscal and external accounts, although the benefits could be partly eroded by volatile capital flows.

Source: punchng.com

FOLLOW US ON:
FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Trending