Connect with us

Business

Oil Price Hits $120 As OPEC+ Raises Output By 206,000 Bpd

Published

on

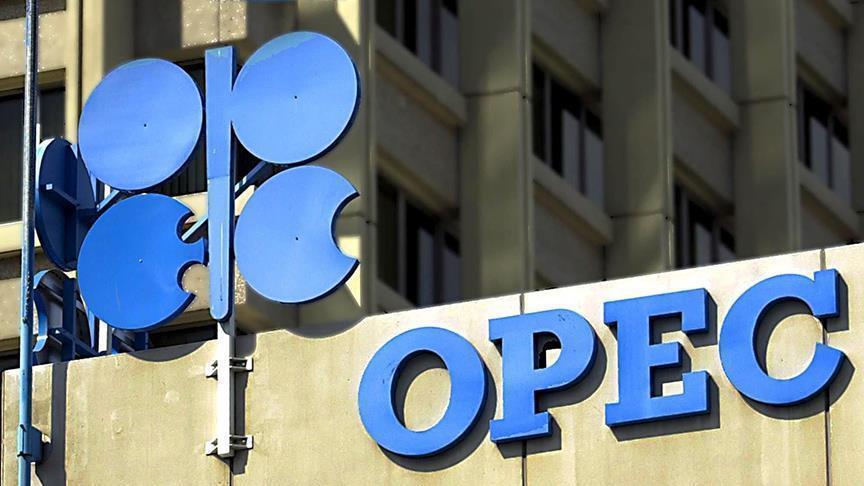
Eight members of OPEC+ have agreed to increase oil output quotas for May by 206,000 barrels per day, even as ongoing geopolitical tensions continue to disrupt global supply.

It was reports that the decision was reached during a virtual meeting held on Sunday, according to a statement released by the oil alliance.

However, despite the announced increase, industry observers say the additional supply may remain largely theoretical due to production constraints affecting key member countries.

Findings indicate that the modest quota increase may not translate into actual output, as major oil producers are grappling with disruptions linked to the ongoing U.S.-Israeli war with Iran.

Several top producers have seen their capacity hampered, with infrastructure damage and security concerns preventing meaningful increases in supply.

Meanwhile, a separate panel of the alliance, the Joint Ministerial Monitoring Committee, also met on Sunday and raised alarm over persistent attacks on oil infrastructure.

The committee noted that such attacks are “expensive and time-consuming to repair,” warning that they continue to weigh heavily on global supply.

The situation is further complicated by disruptions in the Strait of Hormuz, widely regarded as the world’s most critical oil transit route.

The waterway has effectively remained shut since late February due to the conflict, significantly cutting exports from key producers including Saudi Arabia, United Arab Emirates, Kuwait, and Iraq.

Although Iran stated on Saturday that Iraq could freely transit the strait, and shipping data showed a tanker carrying Iraqi crude passing through on Sunday, uncertainty persists.

“It remains to be seen if more vessels will take the risk involved,” a source familiar with the development said.

See also  Petrol imports crash by N2tn to N87bn; see why

Global crude oil prices have surged to nearly $120 per barrel, marking a four-year high, as supply disruptions continue to tighten the market.

The spike has triggered a ripple effect, with transport fuel prices rising sharply and putting pressure on consumers and businesses worldwide. Governments are also beginning to take steps aimed at conserving dwindling supplies.

Analysts warn that prices could climb even higher if the situation persists. Investment bank JPMorgan Chase projected that oil prices may exceed $150 per barrel if disruptions in the Strait of Hormuz extend into mid-May.

Despite the quota adjustment, the additional 206,000 barrels per day accounts for less than two per cent of the estimated supply lost due to the Hormuz closure.

Sources within the alliance told Reuters that the move primarily signals readiness to ramp up production once conditions stabilise and the key shipping route reopens.

Sanctions, Infrastructure Damage Hinder Output

Beyond the Gulf region, other producers are also facing challenges.

Russia, for instance, has been unable to increase production due to Western sanctions and damage to oil infrastructure linked to its ongoing conflict with Ukraine.

The scale of the current disruption is unprecedented, with estimates suggesting that between 12 million and 15 million barrels per day, up to 15 per cent of global supply, have been cut off from the market.

This marks one of the largest oil supply shocks on record.

It was reports that the May increase mirrors the 206,000 bpd adjustment agreed for April during the alliance’s previous meeting on March 1, just as the conflict began to impact oil flows.

See also  CBN announces new withdrawal limit, removes deposit cap

OPEC+, which comprises 22 member countries, has in recent years relied on a core group of eight nations to make monthly production decisions.

These countries had collectively increased output by about 2.9 million barrels per day between April and December 2025 before pausing adjustments from January to March 2026.

With the next meeting scheduled for May 3, attention will be on whether the alliance can respond effectively to the evolving crisis.

FOLLOW US ON:

FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Business

US Government Warns American Business Executives About Investing In Nigeria

Published

on

A United States Department of State report has warned American business executives in Nigeria.

The department warned that insecurity, corruption, port inefficiencies, and regulatory uncertainty could significantly hinder investment in Nigeria.

It was reports that the department gave the warning in its 2026 Investment Climate Statements on Nigeria.

The report explained that those challenges continue to weigh on the country’s business environment despite signs of macroeconomic stability.

The department said the country’s investment landscape has been shaped by the outcomes of “painful but necessary” structural reforms introduced by the President Bola Tinubu administration.

The report said the removal of fuel subsidies and liberalisation of the foreign exchange market initially triggered significant economic volatility, although early 2026 indicators suggested some stabilisation.

However, it warned that security concerns, administrative bottlenecks and the social consequences of economic reforms remain significant considerations for foreign investors.

“The security environment is a primary variable which gives pause to potential investors,” the report said.

It noted that although attacks on oil infrastructure in the Niger Delta have decreased, oil theft and illegal bunkering persist.

In the North, the expansion of terrorist and ‘bandit’ groups continues to degrade the climate for agribusiness and mining,” the document added.

The report also raised concerns about how regulators treat foreign business executives in disputes, citing the detention of Tigran Gambaryan, a US citizen and Binance executive, for nearly eight months in 2024.

“Furthermore, the use of coercive exit bans and detentions, highlighted by the high-profile nearly eight-month detention in 2024 of U.S. citizen Binance employee Tigran Gambaryan, serves as a cautionary note for foreign executives regarding the risks of aggressive regulatory friction,” it said.

See also  CBN announces new withdrawal limit, removes deposit cap

The report said such cases could shape perceptions of Nigeria as a destination for foreign investment.

The department identified inefficiencies at Nigerian seaports as another major challenge for businesses, particularly those dependent on imports and exports.

“Port inefficiency remains a significant ‘hidden tax’ on investment,” the report said.

It noted that the Lekki Deep Seaport handled $9.6 billion in trade in 2025 and operated at 50 per cent capacity, helping to ease pressure on older facilities.

FOLLOW US ON:

FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

Nigerian states’ revenues rise 93%, but education spending drops — World Bank

Published

on

The World Bank says Nigeria’s 36 states recorded a 93 per cent increase in revenues between 2023 and 2025 but education received a declining share of the sector’s expenditure.

The bank disclosed this in its latest Nigeria Development Update, which examined how increased public revenues have influenced spending priorities across the federation.

The report was made available to the News Agency of Nigeria by the World Bank in Washington D.C.

According to the report, states’ aggregate revenues rose by approximately 93 per cent in real terms, while expenditure increased by 92 per cent during the period.

The report attributed the improvement partly to exchange-rate reforms, petrol subsidy removal, stronger revenue administration and increased allocations from the federation account.

It said states also benefited from refunds, settlement of longstanding federal obligations, intervention funds, and stronger Value Added Tax collections.

However, education’s share of total state expenditure declined from 14.9 per cent in 2021 to 12.1 per cent in 2025, according to the report.

Health expenditure remained broadly stable at approximately seven per cent, while social protection’s share increased from 1.4 per cent to 4.4 per cent.

The bank said capital expenditure increased significantly, accounting for 61 per cent of state spending, compared with 46 per cent previously.

Transport infrastructure recorded the largest increase, alongside substantial spending on housing, agriculture and other economic investments.

The report quoted Mathew Verghis, the World Bank Country Director for Nigeria, as saying that increased revenues provided the opportunity to improve infrastructure, education, healthcare, and water services.

See also  Nigerian billionaire Tonlagha hires lobbyists to push Nigeria-US ties

He said greater spending efficiency, accountability and improved service delivery were essential to ensuring that additional public resources benefited Nigerians.

The bank acknowledged improvements in states’ fiscal reporting, transparency and internally generated revenue.

It, however, stressed that stronger investment in human capital was necessary to translate economic reforms into sustainable employment and improved living standards.

The report also projected average economic growth of 4.4 per cent between 2026 and 2028, subject to sustained reforms and improved service delivery.

It urged federal and state authorities to ensure that increased public revenues translated into tangible improvements in Nigerians’ welfare.

NAN

Source: punchng.com

FOLLOW US ON:
FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

Nigeria promotes investment without building production capacity – UNILAG don

Published

on

A professor of Comparative Political Economy at the University of Lagos, Adelaja Odukoya, has asserted that Nigeria’s economic policies promote investment without sufficiently strengthening domestic production.

Odukoya argued that the contradiction had weakened the country’s productive foundations, with policies encouraging investment and entrepreneurship while failing to create the technological capacity, productive employment and processing industries needed to drive sustainable development.

Odukoya spoke at the maiden edition of the Adeleke University Toyin Falola Annual Lecture, held on Thursday at the Performing Arts Theatre, Adeleke University, Ede.

The lecture had as its theme, “History, Power and Accumulation: Reimagining Africa in the Globally Disorderly Order.”

Odukoya identified several contradictions in the way the Nigerian state manages economic activity.

He said, “The state promotes investment without creating conditions for technological transfer. It encourages entrepreneurship without generating sufficient productive employment.

“It expands primary-product exports while leaving processing capacity undeveloped. It constructs infrastructure without establishing strong linkages with domestic production.”

According to him, the contradictions explain why increased economic activity and accumulation do not necessarily translate into development.

“Accumulation is not synonymous with development,” Odukoya stated.

He argued that genuine development should be measured by the expansion of productive, technological, institutional and human capabilities.

“A country could attract investment, export minerals and agricultural commodities and record economic activity while still failing to build the domestic industries and technological capabilities required for long-term development,” he said.

His argument was echoed by Prof Toyin Falola, who said Africa’s vast natural resources would continue to reinforce dependency unless governments developed the industrial, technological and institutional capacity to transform them into productive power.

See also  14 banks have met CBN’s new capital requirement

Falola said Africa’s resource problem was not simply one of historical exploitation, but also the continent’s failure to convert its resource endowments into power.

“The issue, however, is not just to repeat the history of exploitation. It is more important to know how Africa turns its great resources into power,” Falola said.

He argued that Africa could not afford to remain a spectator as global economic and geopolitical arrangements continued to change, stressing that resource ownership without the capacity to add value would not guarantee influence.

Falola said the continent required a combination of knowledge, government policy and industrial capacity to change its economic position.

“There must be universities that generate new knowledge; there must be governments that translate this knowledge into policies; there must be industries that add value to the continent’s natural resources,” he said.

He added that Africa needed more than improved infrastructure and stronger economies if it wanted to exercise greater influence in the global system.

“The future of the continent will require more than just better infrastructure, improved economies, and more effective political institutions,” Falola said.

Source: punchng.com

FOLLOW US ON:

FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Trending