Connect with us

Business

Banks: Bad loans rise after CBN ends forbearance

Published

on

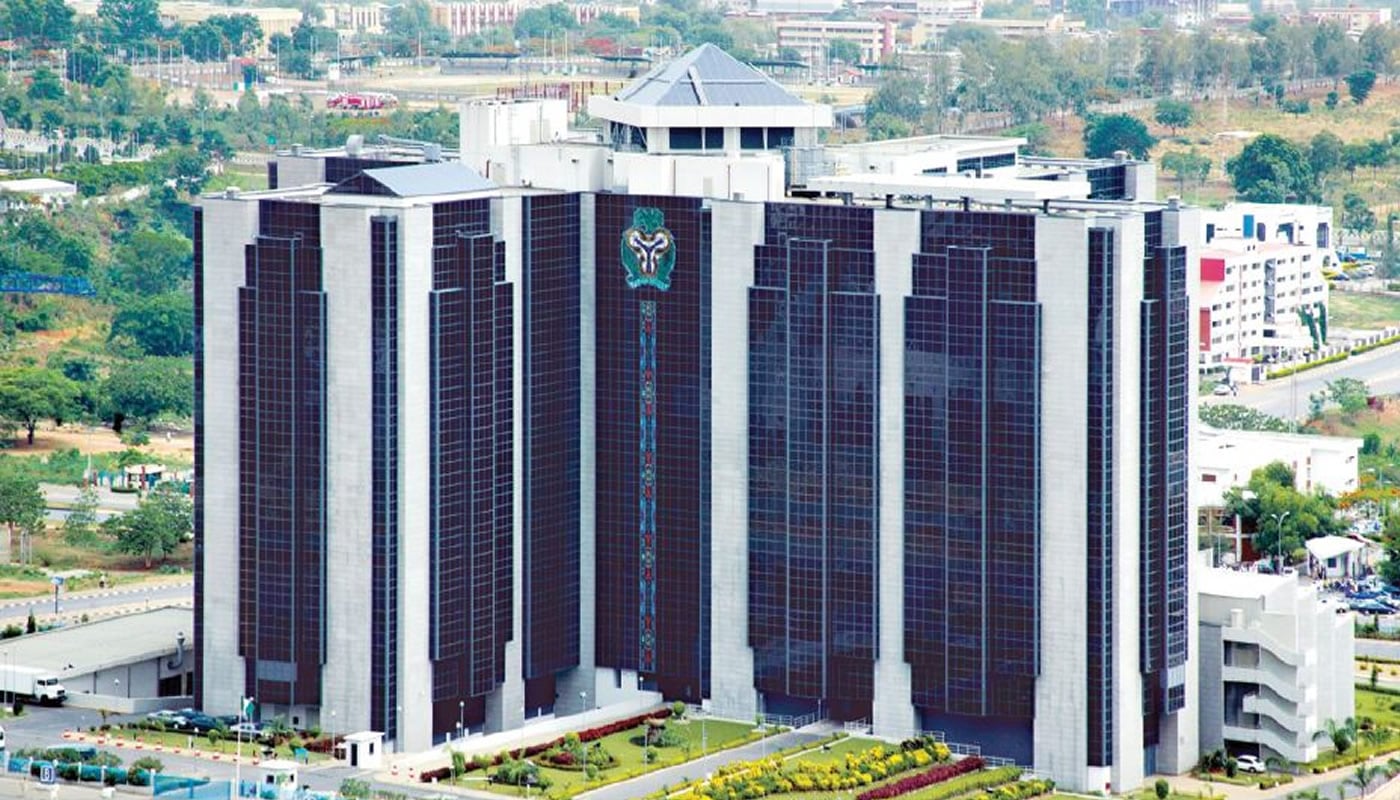
Bad loans in Nigeria’s banking sector rose to 8.03 per cent in January 2026, seven months after the Central Bank of Nigeria moved to end regulatory forbearance granted to banks on some credit exposures and single obligor limit breaches.

The figure, contained in the CBN’s January 2026 Economic Report, showed that the industry’s non-performing loans ratio rose by 0.52 percentage point from 7.51 per cent in December 2025.

It also remained above the CBN’s prudential threshold of five per cent, indicating a further deterioration in asset quality across the banking industry despite the apex bank’s insistence that the sector remained resilient.

The report said, “Following the bank’s loan reclassification after the withdrawal of forbearance, the non-performing loans ratio rose by 0.52 percentage point to 8.03 per cent compared with the level in the preceding period and was above the 5.00 per cent prudential threshold.”

The development came after the CBN, in June 2025, directed banks still benefiting from regulatory forbearance on credit exposures or single obligor limit waivers to suspend dividend payments, defer bonuses to directors and senior management, and halt fresh investments in foreign subsidiaries or offshore ventures.

The regulator said the measure was aimed at strengthening capital buffers, improving balance sheet resilience, and forcing affected banks to retain earnings while exiting temporary regulatory reliefs.

In a separate transition measure, the apex bank also moved to terminate COVID-19-related regulatory forbearance and waivers on single obligor limits effective June 30, 2025, requiring banks to align affected credit exposures with existing prudential guidelines.

Regulatory forbearance had allowed banks to restructure loans affected by the pandemic without immediately classifying them as non-performing. With the withdrawal of the measure, a number of previously restructured facilities have now crystallised as bad loans, pushing the industry ratio above the regulatory ceiling.

The latest NPL reading suggests that the clean-up is beginning to expose weaker loans that had previously been cushioned by regulatory reliefs. Once those loans were reclassified, banks had to recognise more credit weakness on their books, pushing the industry’s bad loan ratio further above the regulatory limit.

See also  US cuts Nigerian crude imports by nearly 50%

In its macroeconomic outlook report, the CBN warned that a “significant rise in non-performing loans could impair asset quality and weaken banks’ balance sheets, thereby posing systemic risk,” showing the importance of monitoring credit risk and sustaining prudential discipline.

It also recommended deepening “the operational integration of the GSI framework across all financial institutions to enhance loan recovery efficiency and credit discipline.”

The CBN also recommended strengthening credit discipline and reducing non-performing loans by fully integrating the Global Standing Instruction framework to boost loan recovery efficiency.

Earlier, in February 2025, the apex bank ordered bank directors with non-performing insider-related loans to step down immediately. Insider loans refer to loans granted by a bank to its own executives, directors, employees, major shareholders, or related parties.

According to the CBN, the decision aims to strengthen corporate governance and improve risk management in the banking sector. To minimise financial risks, the apex bank instructed banks to recover debts through collateral enforcement and seize the shareholdings of affected directors.

“Directors with non-performing insider-related facilities are required to step down immediately from the board, while the bank should commence immediate remediation of the loans through the recovery of the collateral, including the shareholdings of the affected directors,” the circular read.

More recently, the CBN directed banks to deny certain banking services and additional credit facilities to large borrowers with non-performing loans as part of measures to strengthen credit discipline in the banking sector. The directive was contained in a letter dated March 12, 2026, and signed by the Director of Banking Supervision, Dr. Muhammad Abdullahi.

Under the directive, borrowers whose loan facilities have been classified as non-performing and recorded in the Credit Risk Management System or any licensed private credit bureau will no longer be eligible to obtain additional credit from banks.

See also  Inside Abuja, ‘business centres’ disguised as schools

The apex bank said the measure was designed to reduce risks posed by large borrowers whose defaults could threaten financial system stability. “Effective immediately, all financial institutions shall: Restrict further credit access: Any large-ticket obligor with a non-performing facility recorded in the CRMS and/or any licensed private credit bureau shall not be granted additional credit facilities.

“For the purpose of this restriction, credit facilities include loans and other forms of direct credit. In addition, such obligors shall not be granted banking facilities or contingent liabilities such as bankers’ confirmations, letters of credit, performance bonds, or advance payment guarantees,” the bank said.

The CBN explained that the restrictions apply to borrowers classified as large-ticket obligors under the prudential guidelines for deposit money banks. According to the regulator, such borrowers include individuals or companies whose combined exposure across banks exceeds the Single Obligor Limit or whose financial obligations could significantly affect a bank’s capital adequacy ratio.

The bank also directed financial institutions to obtain additional realisable collateral from affected borrowers to adequately secure existing loan exposures. It said the determination of affected borrowers would rely on information captured in the Credit Risk Management System and reports from licensed private credit bureaus.

However, the CBN maintained that the wider banking system remained stable. The report showed that the industry’s liquidity ratio improved to 63.38 per cent in January from 57.22 per cent in December, staying well above the 30 per cent prudential minimum.

The capital adequacy ratio stood at 12.05 per cent, lower than 12.35 per cent in December, but still above the 10 per cent regulatory minimum. According to the CBN, “The Nigerian banking industry remained resilient, with most financial soundness indicators staying within prudential regulatory thresholds, affirming financial stability and institutional soundness.”

See also  Onyema warns new taxes could cripple airlines

The figures indicate a mixed picture for the banking sector. Liquidity remains strong, and capital levels are still above the minimum benchmark, but the rise in bad loans points to pressure from legacy exposures, currency devaluation, high interest rates, and tighter regulatory classification.

The worsening asset quality in the banking sector also drew concern from members of the CBN’s Monetary Policy Committee during its February 2026 meeting, with policymakers warning that rising bad loans could threaten financial stability despite broader improvements in macroeconomic conditions.

The CBN’s Deputy Governor for Economic Policy, Dr Muhammad Abdullahi, said increasing non-performing loans had emerged as a key risk to the financial system and could undermine the effectiveness of monetary policy transmission if left unchecked. “Additionally, rising NPLs could pose financial stability risks, and the broader macroeconomy needs to rebalance growth and stability objectives,” Abdullahi said.

The deputy governor noted that the challenge was occurring alongside persistent excess liquidity in the banking system, warning that both factors could weaken the impact of monetary policy measures and limit the efficient flow of credit to productive sectors of the economy.

Echoing similar concerns, MPC member and corporate governance expert Aku Odinkemelu said the increase in bad loans required closer regulatory scrutiny. “The increase in Non-Performing Loans within the banking system… underscores the need for heightened supervisory vigilance to safeguard asset quality and ensure effective credit transmission,” Odinkemelu said.

The comments suggest that while the banking sector remains broadly resilient, regulators are increasingly focused on the quality of loan assets as the industry adjusts to stricter prudential rules following the withdrawal of regulatory forbearance.

punch.ng

FOLLOW US ON:
FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Business

Read how Nigerians tap savings, loans to buy Dangote refinery shares

Published

on

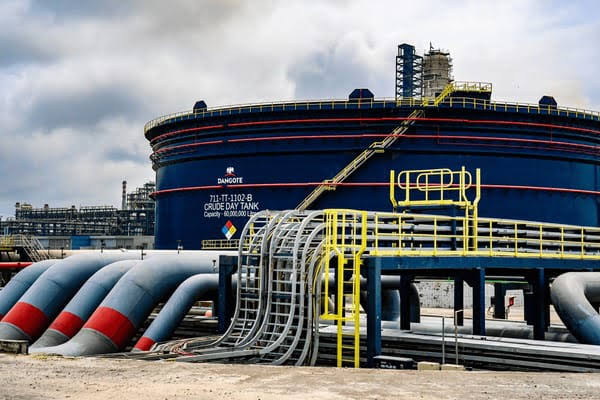
Some Nigerians seeking to invest in the Dangote Petroleum Refinery and Petrochemicals FZE Initial Public Offering have turned to personal savings, loans and proceeds from the sale of assets to raise funds to buy shares, Saturday PUNCH has learnt.

Findings by our correspondents revealed strong interest in the shares among prospective retail investors, some of whom said they expected the investment to yield substantial returns in the future.

While some respondents said they were dipping into savings or raising funds through other means, others said the prevailing economic hardship had made it difficult for them to participate in the offer.

The refinery opened its IPO on Monday, September 14, giving Nigerians an opportunity to own equity in the company.

The offer comprises 4.1 billion ordinary shares priced at N525 each, with the company targeting about N2.15tn to part-fund an expansion that would nearly double the refinery’s capacity to 1.4 million barrels per day.

The minimum subscription is 10 shares, costing N5,250.

Dangote Group Chief Executive Officer, Aliko Dangote, said the low entry threshold was deliberately set to allow ordinary workers, including drivers, cooks and domestic staff, to become shareholders, describing the offer as “the IPO for the people.”

The offer is expected to close on October 13.

Investors turn to savings, loans

A staff member of the Federal Ministry of Works, David Adelabu, described the shares as expensive for struggling civil servants but said he considered the offer an opportunity to become a shareholder in the refinery.

He said, “I have small shares in some companies, including Glo and MTN, but Dangote’s shares will be the highest I will be buying. It is on the high side, but I feel this is an opportunity to become a shareholder in Dangote.

“I understand that the dividends are not going to be immediate, but I don’t mind even if it will entail selling a plot of land I have in Metumbi here in Minna. I will gladly do so.”

A trader in Dutse, Jigawa State, Adamu Bala, said he planned to use savings from his business to buy the shares.

See also  Onyema warns new taxes could cripple airlines

“I will not sell my house. I will use a small profit from my shop to buy,” he said.

Similarly, a civil servant, Fatima Mannir, said women in her group had started raising money through contributions, known as adashe, to participate in the offer.

“We have started raising money through adashe,” she said.

A trader in Damaturu, Yobe State, Malam Musa Ibrahim, said he invested part of his business savings after learning about the offer.

“I am using part of the money I have saved from my business.

“I believe that if I can invest a small amount now, it may become useful to me in the future. But I am also being careful because business is not easy at the moment,” he said.

Another resident, Aisha Mohammed, said she raised money by cutting down on some household expenses.

“I did not borrow money to buy the shares. I have been saving little by little, and when I heard about the offer, I decided to use part of what I had saved,” she said.

A businessman, Abdullahi Yusuf, however, said he obtained financial assistance from a friend to increase his subscription.

“I wanted to buy more shares than what my savings could afford, so I discussed it with a friend who agreed to lend me some money.

“I know that borrowing money to invest carries risks, but I am hoping that the investment will perform well. I will repay the money from my business income,” he said.

A petty trader, Hauwa Lawan, said she sold some personal belongings she no longer used and added the proceeds to her savings to finance her purchase.

“I sold some things that I was no longer using and added the money to my savings,” she said.

A farmer, Mallam Abdullahi Adamu, said he sold farm produce to raise about N500,000 to invest in the shares.

In Kano State, an investor, Abdulmalik Ibrahim, said he bought 10 shares for N5,250 using personal funds.

Hardship keeps some investors away

While some Nigerians are finding ways to participate in the IPO, others said economic pressures had put the investment beyond their reach.

See also  Inside Abuja, ‘business centres’ disguised as schools

A civil servant in Kogi State, Saliu Joseph, said he would have loved to invest but had just paid his children’s school fees.

“Right now, I don’t think I can afford to participate unless a miracle happens,” he said.

A retired permanent secretary in the state, Bola Boro, also said he would not participate because he could not afford the investment at the moment.

“As a retired civil servant, I cannot afford such an amount to invest in the offer. Even though I am a fan of investment through the stock market, which I have been doing for years, I don’t think it will be convenient for me to participate considering the time frame of just one month,” he said.

A civil servant, Kuta Abdulahi, said the financial demands of his children’s education had left him unable to participate in the share offer.

“I must tell you the truth, I know about the Dangote Refinery shares, but I cannot even think of it at this time. My children are just resuming a new term in school. Where will I get the money for their school fees before thinking of buying shares? Please, I have a lot on my head,” he said.

Similarly, a vulcaniser, Ahmed Alkali, said his income was barely enough to meet his family’s basic needs, making investment in shares difficult.

“With the kind of job I do, I am working from hand to mouth. So, how can I buy shares when I have not eaten?” he asked.

Experts warn against borrowing

Investment experts, however, cautioned Nigerians against taking loans, selling properties or committing all their savings to the IPO, warning that equity investments carry risks.

Speaking with Saturday PUNCH, the Group Managing Director of Lancelot Group, Adebayo Adeleke, urged prospective investors to understand the risks associated with the capital market before committing their funds to the IPO.

Adeleke, who is also a former Secretary of the Independent Shareholders Association of Nigeria, said capital market investments should be made with funds that investors could afford to leave untouched for the long term, noting that equities were unsuitable for people struggling to meet immediate financial needs.

He said, “When you buy shares, you are buying a portion of the ownership of the business. Investment takes a lot of time to pass through gestation, to stability, to profitability. And you cannot, with any degree of certainty, predict when the company is going to turn the corner and begin to produce profits.

See also  Breaking: Marketers Announce Intention To Increase Petrol Price After Dangote’s Fresh Decision

“So, investment money is not the money you are likely to need in the next two months, three months, six months, even one year. If you cannot part with your money for a minimum of three to five years, the capital market is not the place to invest.”

Adeleke, however, described the IPO as a strategic investment, citing the refinery’s scale and demand for its products.

Also speaking, the Head of Financial Institutions Ratings at Agusto & Co., Ayokunle Olubunmi, urged Nigerians to consider the risks associated with the investment and avoid committing all their savings to the offer.

He said, “There are plenty of risks to this business. It’s not risk-free. Things can get worse for the business. Valuation is based on expectations of what will happen in the future. Things might not go as planned. And, like we all know, equity is a risky business.”

Olubunmi particularly cautioned prospective investors against selling property or using up all their savings to invest in the offer.

He advised them to invest only a portion of their funds and diversify their portfolios.

The expert also advised those considering taking loans to buy the shares to have a separate and reliable repayment plan rather than depending on returns from the investment.

The Emir of Kano, Muhammadu Sanusi II, had earlier warned prospective investors against using their children’s school fees or selling their homes to invest in the shares.

Sanusi, who gave the warning on Thursday while speaking at the company’s roadshow in Kano, urged prospective investors to invest only money they could afford to set aside for some time, suggesting amounts such as N10,000, N20,000 or N30,000.

Source: punchng.com

FOLLOW US ON:

FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

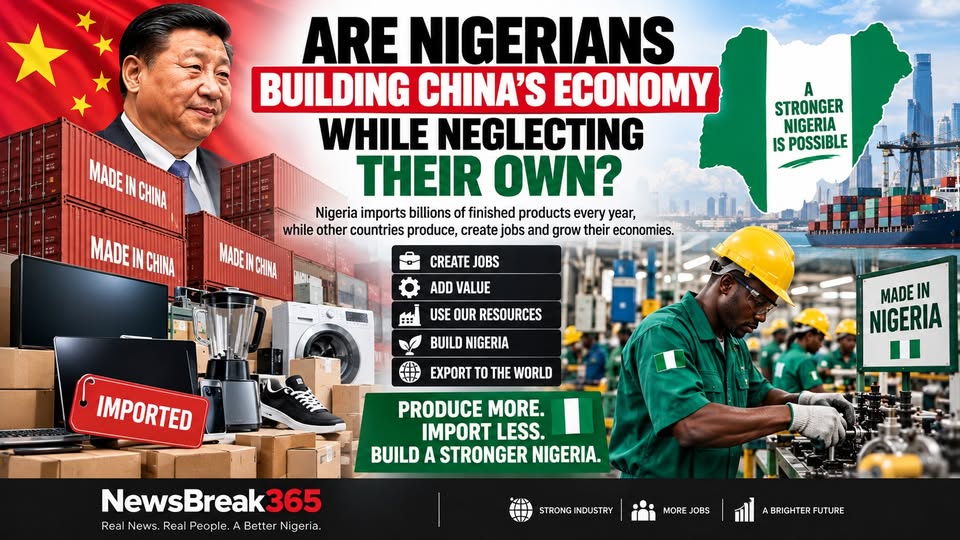
ARE NIGERIANS BUILDING CHINA’S ECONOMY WHILE NEGLECTING THEIR OWN?

Published

on

While other nations are busy producing, manufacturing and exporting, Nigeria must ask itself a difficult question: Are we building our own economy, or simply creating a bigger market for other countries?

Nigeria has a huge population, abundant natural resources and a massive consumer market. Yet the country continues to depend heavily on imported finished products—from electronics and clothing to machinery, household goods and other consumer items.

The issue is not simply about Chinese businesses or businesses from any other foreign country operating in Nigeria. Foreign investment can bring capital, technology, jobs and expertise.

The bigger issue is whether **Nigerian businesses are being given the opportunity and support to manufacture competitively at home.

Instead of remaining primarily a consumer of finished products, Nigeria needs to strengthen its manufacturing sector and move further up the value chain.

Nigeria needs to produce, not just consume.

A stronger manufacturing economy could help Nigeria:

* Create more jobs for Nigerians
* Add value to locally available raw materials
* Develop industrial skills and technology
* Reduce excessive dependence on imported finished goods
* Build competitive Nigerian companies
* Increase the country’s ability to export

The goal should not be to drive legitimate foreign businesses out of Nigeria. The goal should be to build an economy where **Nigerian manufacturers can compete, grow and eventually take Nigerian-made products to markets around the world.

The question Nigerians should be asking is simple:

**Why should Nigeria remain one of the world’s biggest markets for finished products when we have the potential to manufacture many of them ourselves?

See also  Onyema warns new taxes could cripple airlines

🇳🇬 **Nigeria must move from being predominantly a consumer nation to becoming a stronger producer, manufacturer and exporter.

What do you think?

Which products should Nigeria prioritize for local manufacturing instead of relying heavily on imports?

Share your thoughts in the comments.

FOLLOW US ON:
FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

Continue Reading

Business

ICRC defends toll pricing on highways

Published

on

The Infrastructure Concession Regulatory Commission has defended the toll pricing structure under the Highway Development and Management Initiative, saying charges are evaluated against the quality and benefits of the upgraded roads.

In a statement made available to PUNCH Online on Thursday, the Director-General, Dr. Jobson Ewalefoh, cited the 227-kilometre Akwanga–Makurdi road corridor as an example.

He said the route has four toll gates, and motorists pay as they travel along it.

He argued that toll payments should be viewed against the previous costs imposed by the poor condition of the road, including lost man-hours, vehicle damage and accident risks.

Feedback from road users, he said, shows many motorists are willing to pay tolls where they see clear improvements in road quality.

Some drivers have expressed support for similar arrangements on other major corridors if the roads are upgraded to the same standard.

“That, to me, is the beauty of a well-structured PPP,” Ewalefoh said.

He explained that negotiators carefully consider toll pricing to keep charges fair. A portion of the revenue is set aside specifically for road maintenance. Under the concession agreements, the government does not bear additional maintenance costs for the duration of the contract.

The government must repair potholes within 48 hours, and it funds major routine repairs from the dedicated toll revenue.

Source: punchng.com

FOLLOW US ON:

FACEBOOK

TWITTER

PINTEREST

TIKTOK

YOUTUBE

LINKEDIN

INSTAGRAM

See also  US cuts Nigerian crude imports by nearly 50%
Continue Reading

Trending